
- Crypto-Native Since 2016. Built for the Digital Asset Compliance Era.
Cryptocurrency Tax Resolution for Digital Asset Investors
Recognized by Forbes as a Best-in-State Top CPA in 2025 and 2026
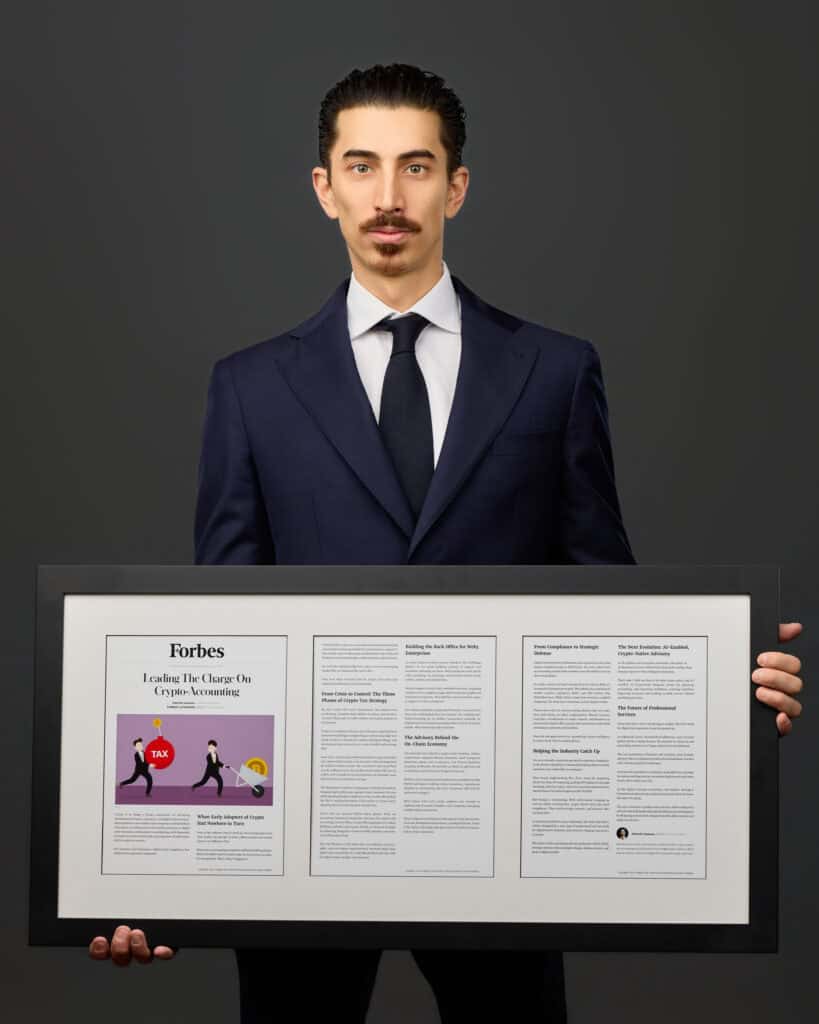
Featured in Forbes for "Leading the Charge on Crypto Accounting": Read the Forbes Feature
Camuso CPA helps digital asset investors address historical tax reporting problems, respond to IRS correspondence, reconstruct supporting records, and resolve cryptocurrency tax matters through documented analysis and authorized representation.
As Seen In:







Digital Asset Taxation in the United States: A Policy Analysis
Co-authored with the former head of the IRS Office of Digital Assets and co-author of the §6045 digital asset broker reporting regulations. Published in Tax Notes Federal and Tax Notes Global.
Read in Tax Notes → Read All Publications →
First U.S. CPA Firm to Accept Cryptocurrency Payments
Original announcement ↗
Resolving Cryptocurrency Tax Problems Requires More Than an IRS Response
Cryptocurrency tax disputes often begin with incomplete records. Missing exchange histories, incorrect cost basis, unreconciled wallet transfers, and unreported digital asset income can create discrepancies between a taxpayer’s records, filed returns, and information available to the IRS.
The appropriate response depends on the actual issue. A CP2000 notice proposes changes based on information-return discrepancies. Cryptocurrency compliance letters such as IRS Letters 6173 and 6174-A have different response requirements. An active examination involves its own procedures, deadlines, and documentation requests.
Camuso CPA evaluates the relevant correspondence, historical filings, and underlying digital asset activity to identify the accounting and tax questions that must be resolved.
Depending on the engagement, our work may involve transaction reconstruction, cost basis analysis, amended or delinquent returns, IRS notice responses, or evaluation of payment and penalty relief options.
We distinguish disputed reporting positions from actual liabilities and develop an appropriate response based on the available evidence and applicable tax authorities. Not every matter requires complete historical reconstruction, and not every IRS notice indicates that additional tax is owed.
Camuso CPA has worked with cryptocurrency accounting and tax matters since 2016. Patrick Camuso, CPA, was recognized by Forbes as a Best-in-State Top CPA in 2025 and 2026, and his digital asset tax research has been published in Tax Notes.
How Our Cryptocurrency Tax Resolution Process Works
Step 1: IRS Notice & Historical Compliance Assessment
We review the relevant IRS correspondence, filing history, available tax records, and digital asset activity to determine the nature of the issue, applicable deadlines, and potential exposure. We identify the information needed and establish the engagement scope before substantive resolution work begins.
Step 2: Transaction Analysis & Supporting Documentation
We investigate the accounting and tax issues underlying the matter. Depending on the circumstances, this may include reviewing IRS transcripts, reconciling exchange information returns, reconstructing historical wallet activity, evaluating cost basis and income classifications, or reviewing previously filed returns.
Step 3: IRS Response, Representation & Compliance Resolution
We prepare the applicable notice responses, corrective filings, supporting documentation, or tax positions. Where authorized under an appropriate power of attorney, we can communicate and represent the client before the IRS within the agreed scope.
Prefer to book a time directly?
Book a Crypto Tax Resolution Consultation →Prefer to reach us directly? Email info@camusocpa.com or call (704) 249-3179.
Who We Help: Crypto Investors, Founders & Web3 Builders
From early Bitcoin adoption through today’s multi-chain digital asset ecosystem, we have advised investors and operators whose crypto exposure is financially material.
- Investors Responding to IRS Notices
- Investors With Unfiled or Incorrect Crypto Tax Returns
- Investors Facing IRS Examinations or Material Tax Disputes
Signs You Need Cryptocurrency Tax Resolution
- You received an IRS notice such as CP2000, Letter 6173, 6174-A, or another exam letter
- You have unfiled returns involving substantial cryptocurrency transactions.
- The IRS is examining your cryptocurrency transactions or requesting documentation you cannot readily produce.
- You have an assessed cryptocurrency-related tax balance and need to evaluate available payment arrangements or penalty relief.
Comprehensive Crypto CPA Services for Digital Asset Investors
From tax resolution and audit defense to ongoing preparation, planning, and portfolio accounting. Every service is built for the complexity of digital asset compliance.
Crypto Tax Cost Basis Reconstruction & Historical Reporting
Reconstruct historical cryptocurrency transactions and establish supported acquisition records when missing or incorrect basis affects an IRS matter.
Form 1099-DA Compliance & Reconciliation Services
Review broker-reported transactions, identify discrepancies, and prepare supporting reconciliation records for tax reporting or notice responses.
Cryptocurrency Portfolio Accounting
Establish and maintain reconciled wallet, exchange, and tax-lot records to support ongoing compliance after historical accounting issues are addressed.
Crypto Tax Preparation & Compliance
Prepare delinquent, current-year, or amended tax returns involving complex digital asset transactions under the applicable engagement scope.
Why Digital Asset Investors Choose Camuso CPA for Cryptocurrency Tax Resolution
Cryptocurrency tax matters frequently require technical accounting work before the underlying reporting questions can be resolved.
Camuso CPA combines experience in historical digital asset transaction reconstruction, tax-lot accounting, DeFi activity, and federal tax analysis. We examine the records supporting the taxpayer’s reporting positions and prepare documentation appropriate to the particular IRS matter.
For complex engagements, our work can connect historical accounting corrections, amended returns, tax-position analysis, and IRS representation within a coordinated process. We also work alongside existing tax attorneys and other advisers when responsibilities are clearly defined.
Patrick Camuso has worked with digital asset accounting and taxation since 2016, and his research on digital asset taxation has been published in Tax Notes.
Facing an IRS Crypto Tax Issue? Get Expert Resolution From a Forbes-Recognized Crypto CPA.
IRS Letter 6174-A — Ten Years of Cryptocurrency Records Reconstructed Following IRS Compliance Correspondence
The Problem
A cryptocurrency investor received IRS Letter 6174-A after years of digital asset activity across multiple exchanges, wallets, and blockchain protocols.
Historical accounting records were incomplete, and earlier tax returns had relied on software-generated reports containing cost basis and transaction classification discrepancies. The investor needed to evaluate prior reporting and establish documentation supporting the appropriate tax treatment of historical transactions.
What We Did
Camuso CPA reviewed the IRS correspondence, historical tax filings, and available digital asset records to identify material accounting and reporting questions.
Our work involved reconstructing historical cryptocurrency activity, reconciling wallet and exchange transactions, reviewing cost basis records, and investigating income classification discrepancies.
We prepared supporting accounting documentation and evaluated the appropriate treatment of identified prior-year reporting issues.
The Outcome
The engagement established reconstructed historical transaction records and supporting tax workpapers for the periods reviewed. Material accounting discrepancies were documented, providing a more reliable foundation for evaluating prior filings and maintaining future compliance.
The client gained a clearer understanding of the historical accounting and tax issues, together with records to support appropriate corrective action where required.
Resolve Your Crypto Tax Issue. Protect Your Digital Assets.
Trusted cryptocurrency tax resolution for individual digital asset investors. From unfiled returns to active IRS audits.
"Patrick is a fantastic accountant and is fluent with crypto and crypto-regulations."
Cryptocurrency Tax Resolution FAQ's
What is cryptocurrency tax resolution?
Cryptocurrency tax resolution involves addressing tax reporting and compliance issues arising from digital asset activity. These matters may include IRS notices, unfiled returns, incorrect historical filings, disputed tax positions, examinations, or assessed tax balances.
The work may require reconstructing historical transactions, establishing reliable cost basis records, reviewing prior returns, preparing corrective filings, and communicating with the IRS.
Camuso CPA evaluates the accounting and procedural issues involved and establishes a resolution strategy appropriate to the taxpayer's circumstances.
What should I do if I receive a CP2000 notice involving cryptocurrency?
An IRS CP2000 notice generally identifies differences between information reported by third parties and amounts reported on a taxpayer's return. It proposes adjustments but is not itself a tax assessment, bill, or IRS audit.
Review the notice, identify the transactions and tax years involved, and compare the proposed adjustments with your accounting records and filed return. Follow the response deadline and instructions stated in the notice.
If the proposed amounts are incorrect, supporting records and an explanation may be needed. Camuso CPA can review cryptocurrency transaction histories, analyze the proposed adjustments, and prepare an appropriate response under an agreed engagement.
What is the difference between IRS Letters 6173, 6174-A, and an IRS audit?
IRS Letters 6173 and 6174-A are cryptocurrency-related voluntary compliance letters. They do not, by themselves, establish that a formal tax examination has begun.
Letter 6173 generally requires a response by the stated deadline. Letter 6174-A generally advises taxpayers to review their cryptocurrency reporting and does not require a direct response.
An IRS examination is a separate process in which the agency reviews returns, transactions, and supporting documentation. Regardless of the type of letter, taxpayers should review their historical reporting and address errors where appropriate.
Can the IRS identify cryptocurrency transactions, including DeFi activity?
The IRS receives digital asset information from multiple sources, including applicable broker reporting, taxpayer filings, and information obtained through compliance and enforcement procedures.
Transactions on public blockchains may also provide records that can be analyzed alongside exchange, wallet, and other information. However, not every transaction or wallet can necessarily be attributed to a particular taxpayer from publicly available blockchain information alone.
DeFi transactions and other self-custody activity may create taxable events even when no broker-issued information return is provided. Taxpayers remain responsible for reporting applicable income and transactions.
What if I have several years of unfiled cryptocurrency tax returns?
Multiple years of unfiled cryptocurrency tax returns may require historical transaction reconstruction, income analysis, cost basis reconciliation, and evaluation of filing requirements for each year.
The appropriate approach depends on the taxpayer's filing history, available records, amounts involved, prior IRS correspondence, and other relevant circumstances.
Camuso CPA can evaluate the historical accounting and tax issues, determine the work needed to prepare delinquent returns, and assess appropriate compliance procedures. The filing strategy and engagement scope are developed after reviewing the underlying facts.
Should I amend previously filed cryptocurrency tax returns?
An amended return may be appropriate when a prior filing contains material errors involving cryptocurrency transactions, cost basis, income, deductions, or other tax items.
Not every accounting discrepancy automatically requires an amended return. The decision depends on the nature and materiality of the issue, the applicable tax rules, filing deadlines, and whether the error affects the return.
Camuso CPA can review historical records, evaluate potential reporting corrections, and prepare amended returns where appropriate under the agreed engagement scope.
Do I need complete historical cost basis reconstruction to resolve an IRS issue?
Not necessarily. Some IRS matters can be addressed through targeted transaction reconciliation, recovery of missing acquisition records, or analysis of specific reporting discrepancies.
More extensive reconstruction may be required when historical records are unreliable, multiple years are affected, or the taxpayer cannot establish the cost basis or character of material transactions.
Camuso CPA evaluates the nature of the IRS issue and the available evidence before determining whether a targeted accounting engagement or comprehensive historical reconstruction is necessary.
Can cryptocurrency-related IRS penalties be reduced or removed?
Certain IRS penalties may qualify for administrative relief or reasonable-cause relief, depending on the type of penalty, tax period, compliance history, and facts of the case.
In 2026, the IRS began transitioning from First Time Abate to Automatic Exemption from Penalty (AEP). AEP can prevent certain failure-to-file, failure-to-pay, and failure-to-deposit penalties for eligible original returns. First Time Abate remains relevant for certain earlier periods and transition cases.
Penalty relief is not automatic for every taxpayer or every liability. Camuso CPA can evaluate eligibility, review supporting circumstances, and assist with appropriate relief requests where applicable.
Can Camuso CPA represent me during an IRS audit or help with tax payment arrangements?
Yes. As a CPA firm, Camuso CPA can provide authorized IRS representation for eligible federal tax matters within the agreed engagement scope. Representation generally requires a properly executed Form 2848 identifying the relevant tax matters and periods.
Depending on the circumstances, the engagement may include examination support, notice responses, review of assessed balances, or evaluation of IRS payment arrangements.
Installment agreements and offers in compromise have separate eligibility rules. Approval depends on the taxpayer's circumstances and applicable IRS procedures. No particular settlement or reduction is guaranteed.
How long does cryptocurrency tax resolution take, and how do I get started?
The timeline depends on the type of IRS matter, number of tax years involved, availability of historical records, complexity of the transactions, and IRS processing requirements.
A targeted notice response may require substantially less accounting work than an engagement involving years of unfiled returns, complex DeFi activity, or historical transaction reconstruction. IRS processing and examination timelines can also vary.
To begin, provide information about the relevant tax years, notices or correspondence, cryptocurrency activity, and available records. Camuso CPA will assess the situation and determine an appropriate engagement scope.