Prediction Market CPA for Trading Firms, Market Makers & Professional Traders

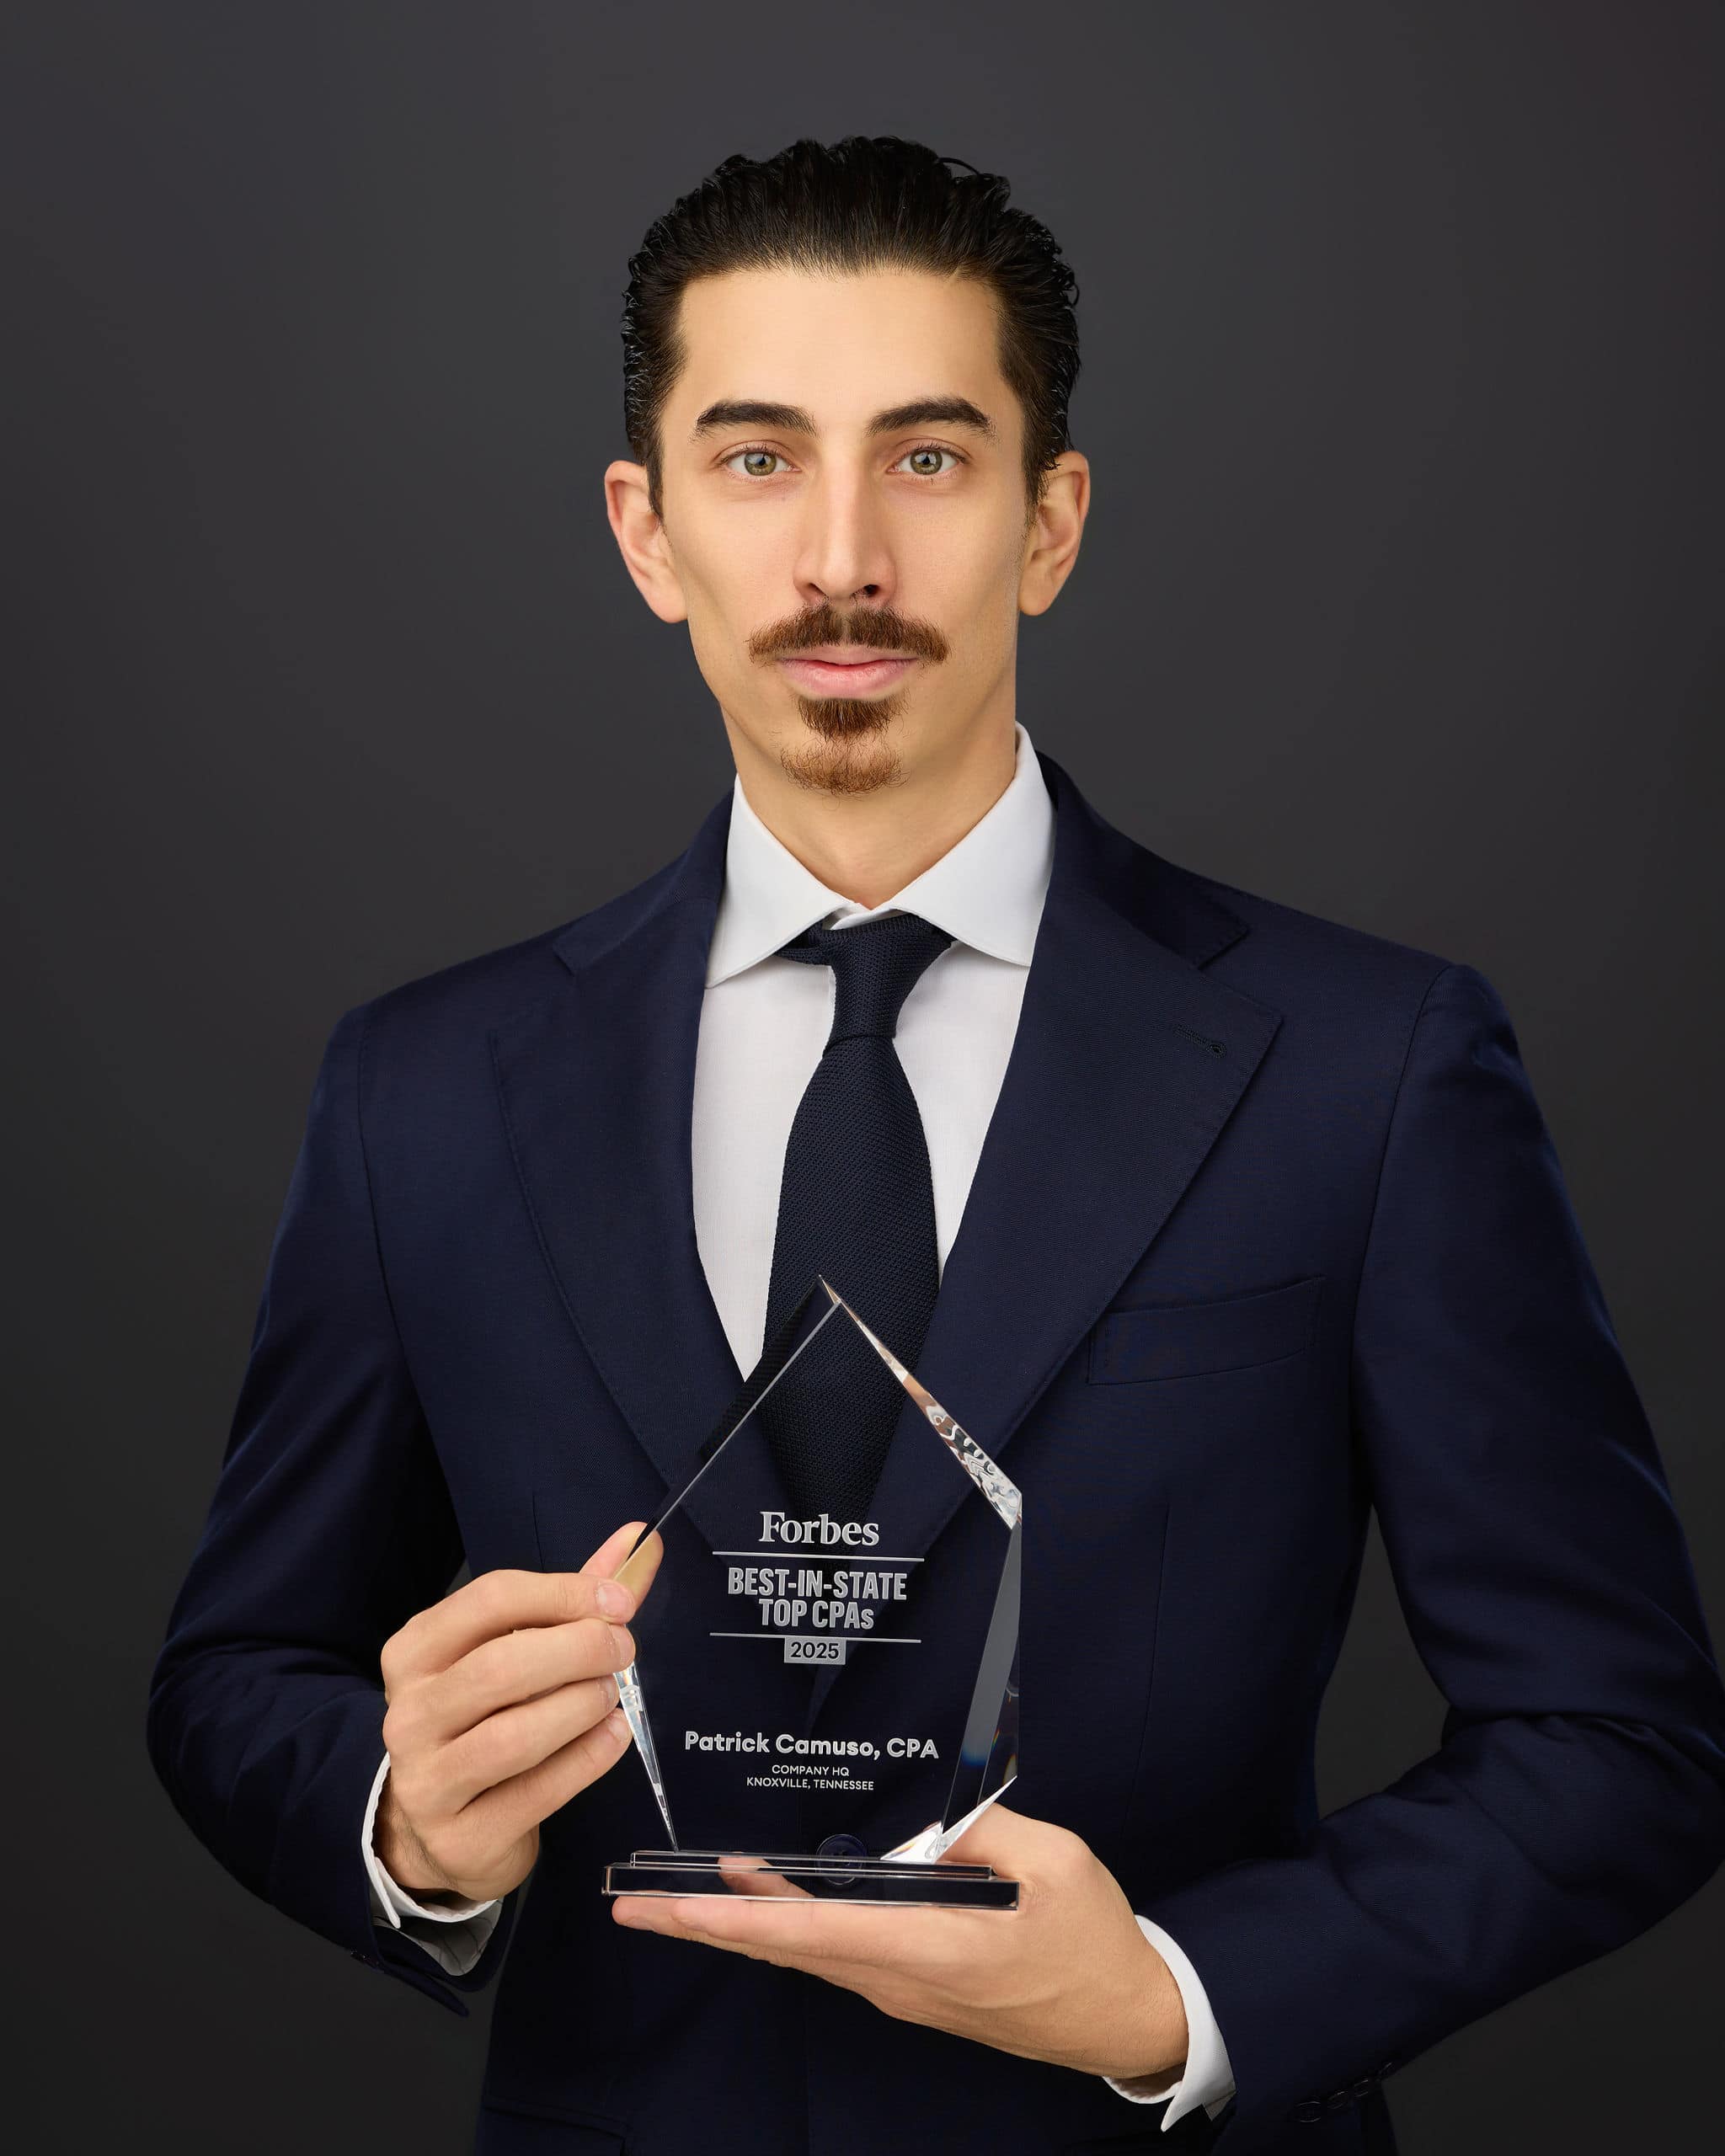
Forbes Best-In-State Top CPA for 2025 and 2026

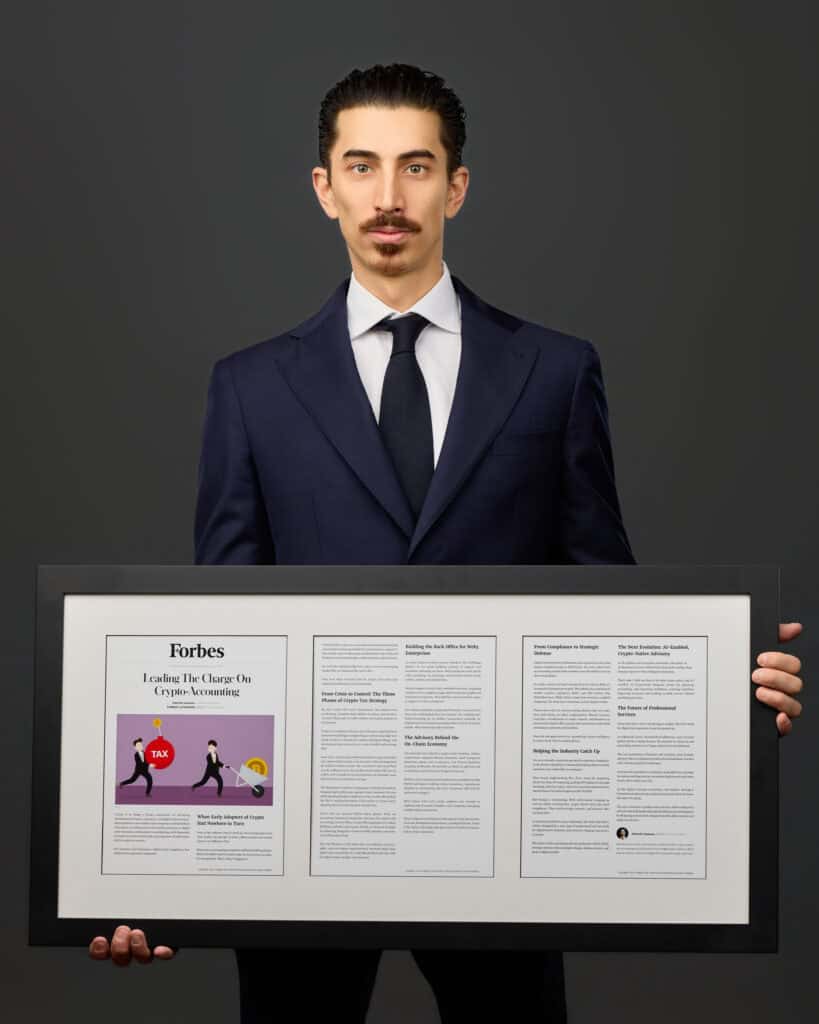
Featured in Forbes for "Leading the Charge on Crypto Accounting": Read the Forbes Feature

Camuso CPA provides specialized accounting and tax services for prediction market traders, market makers, and trading firms. We help clients reconcile activity across Kalshi, Polymarket, and other venues, establish reliable transaction records, analyze complex event-contract tax positions, and meet their reporting and compliance obligations.

As Seen In:

Tax Notes
Federal & Global
Published Research

Prediction Market Event Contracts: A Tax Classification Analysis

Co-authored with the former head of the IRS Office of Digital Assets and co-author of the §6045 digital asset broker reporting regulations. A federal tax classification analysis examining how prediction market event contracts may be treated under §165(d) wagering rules, §1256 contract treatment, and general capital or ordinary income rules. Published in Tax Notes Federal and Tax Notes Global.

Read in Tax Notes → Read All Publications →

Prediction Markets Create Specialized Accounting and Tax Issues

Prediction market trading creates accounting and tax questions that depend on the contracts traded, the way positions are entered and exited, and the taxpayer’s individual circumstances.

Professional traders and market makers may execute substantial volumes across multiple venues, operate systematic or automated strategies, maintain open positions, and receive fees, rebates, or liquidity incentives.

The underlying transaction records are essential to understanding that activity. Contract acquisitions, sales, offsets, transfers, and resolutions may produce different economic and tax consequences.

Reconstructing these events can require detailed execution records, position histories, settlement information, and cash reconciliations. For trading businesses, those records may also need to support a transaction-level subledger, general ledger, period-end close, and financial reporting.

Tax treatment introduces a separate layer of complexity.

Depending on the contracts and relevant facts, the analysis may involve capital or ordinary treatment, wagering provisions, §1256, trade-or-business considerations, income timing, loss limitations, and entity or owner reporting. Regulatory treatment by a trading venue does not automatically establish the applicable federal tax characterization.

Camuso CPA advises both individual professional traders and trading businesses on these matters. Our engagements range from technical tax analysis and return preparation to historical trading-account reconciliation, specialized accounting systems, ongoing financial reporting, and integrated accounting and tax compliance. Clients can engage us for accounting, tax advisory, or both, depending on their needs.

Patrick Camuso | Forbes Best-In-State Top CPA
Patrick Camuso, CPA, founder of Camuso CPA and Forbes Best-in-State Top CPA in 2025 and 2026.

Our Prediction Market Accounting & Tax Process

Step 1: Trading Activity, Entity & Records Review

We review the taxpayer's prediction market activity, venues, trading strategies, transaction volume, entity structure where applicable, available records, prior tax reporting, and existing accounting. This establishes the scope of the accounting, tax analysis, planning, or compliance work required.

Step 2: Accounting & Reconciliation

Where accounting support is needed, we reconcile trading and settlement activity, review position histories, and establish records supporting the relevant reporting requirements. For trading businesses, the engagement may also include transaction-level subledgers, general-ledger integration, and recurring period-end close.

Step 3: Tax Analysis & Planning

We evaluate the treatment of the relevant contracts and transactions based on their terms, economic outcomes, taxpayer capacity, and applicable federal tax authorities. Depending on the engagement, this may include written tax position analysis, entity and owner considerations, estimated-tax planning, and prospective tax decisions.

Step 4: Reporting & Ongoing Support

We apply supported accounting and tax conclusions to the applicable workpapers and filings. Services may include individual or entity tax returns, partnership reporting, recurring financial accounting, quarterly projections, and ongoing tax advisory. The deliverables and reporting cadence depend on the agreed engagement.

Prefer to book a time directly?

Prefer to reach us directly? Email info@camusocpa.com or call (704) 249-3179.

Who We Help: Prediction Market Traders, Market Makers & Trading Firms

Camuso CPA works with individuals and businesses whose prediction-market activity presents complex accounting or federal tax questions. Our clients include high-volume individual traders, algorithmic traders, market makers, proprietary trading firms, and multi-owner trading operations.

Some clients need a technical tax analysis of their contract activity. Others need historical transaction reconstruction, ongoing accounting, financial reporting, or integrated tax compliance. We structure the engagement around the trading activity, reporting obligations, and financial records rather than assuming every trader operates through the same business model.

Ready To Speak With A Prediction Market CPA?

Common Prediction Market Accounting & Tax Issues We Address

Patrick Camuso, Forbes 2025 Best-in-State Top CPA was featured in Forbes for leading the charge on crypto accounting
Patrick Camuso, CPA. Featured in Forbes for Leading the Charge on Crypto Accounting.

Prediction Market Accounting & Tax Services

Camuso CPA provides accounting, tax advisory, and compliance services for sophisticated prediction market activity. We work with individual professional traders, market makers, and trading businesses, with engagements tailored to their reporting requirements and the complexity of their records.

Prediction Market Accounting & Reconciliation

We reconstruct and reconcile prediction-market transactions, contract positions, settlement activity, fees, rebates, and cash movements. For trading businesses, services may include transaction-level subledger accounting, general-ledger integration, and period-end reporting.

Ongoing Accounting & Financial Reporting

For clients requiring recurring support, we provide transaction reconciliation, subledger maintenance, period-end close, financial reporting, and year-end accounting workpapers. The reporting structure and cadence depend on the trading operation and engagement scope.

Prediction Market Tax Analysis & Compliance

We analyze the federal tax treatment of prediction-market contracts, trading outcomes, and related transactions, then apply the supported treatment to applicable tax workpapers and returns. Engagements may include individual, partnership, or corporate tax reporting.

Tax Planning & Written Tax Positions

We advise on material tax positions, trader and entity considerations, estimated taxes, potential elections, and planning surrounding significant trading activity. Where appropriate, we prepare written analysis of the relevant contracts, facts, and federal tax authorities.

Why Prediction Market Traders Work With Camuso CPA

Prediction market tax analysis depends on understanding how the contracts work and what actually happened to each position. Execution records, offsets, sales, settlements, fees, rebates, and other transaction details can affect both the accounting and the factual basis for a federal tax position.

Camuso CPA works directly with professional traders and market makers to address these issues. Our experience includes reconstructing high-volume trading histories, developing prediction-market accounting records and subledgers, analyzing federal tax characterization, and carrying supported conclusions through tax reporting and compliance.

Patrick Camuso has also co-authored research published in Tax Notes examining the federal tax classification of prediction market event contracts, including potential applications of §165(d), §1256, and capital or ordinary income rules. That research reflects the same technical questions we encounter in our client work.

Prediction Market Accounting & Tax

Case Study

Professional Prediction-Market Market Maker — Accounting and Federal Tax Analysis

Client Type Professional Trading Firm
Activity Automated Market Making
Scale Millions of Fills
Focus Accounting, Reconciliation & Federal Tax

The Problem

The firm’s prediction-market activity had reached a transaction volume and level of complexity that required transaction-level accounting beyond platform summaries. The engagement also involved unresolved federal tax issues affecting the treatment and reporting of the firm’s prediction-market activity.

What We Did

Camuso CPA developed transaction-level accounting records and a prediction-market subledger designed to support reconciliation and general-ledger reporting. In parallel, we analyzed the federal tax treatment of the relevant prediction-market activity and documented material reporting positions.

The Outcome

The firm established a coordinated accounting and tax process in which the transaction records supporting the books also provide the factual basis for year-end workpapers and federal tax reporting. The engagement created a consistent connection between the firm’s trading activity, accounting records, and adopted tax positions.

Ready To Speak With A Prediction Market CPA?

Prediction Market CPA FAQ

What does a prediction market CPA do?

A prediction market CPA provides specialized accounting and federal tax support for event-contract trading. Depending on the engagement, the work may include transaction reconciliation, contract-level records, accounting and subledger reporting, federal tax characterization, planning, tax workpapers, and individual or entity tax compliance.

Camuso CPA works with individual professional traders, market makers, and trading firms. Accounting and tax services can be engaged independently or together.

Does Camuso CPA provide ongoing prediction market accounting?

Yes. For clients who need recurring accounting, we provide transaction reconciliation, subledger maintenance, general-ledger integration where applicable, monthly or quarterly close, financial reporting, and year-end workpaper support.

The appropriate scope depends on the trading activity, available source records, and whether the client operates individually or through a business entity.

Do you work with individual traders as well as market makers and trading firms?

Yes. We advise high-volume individual traders, systematic and algorithmic traders, market makers, proprietary trading firms, and multi-owner trading operations.

Individual traders may primarily need contract tax analysis, reporting, and planning. Trading businesses may also require entity accounting, partner reporting, transaction-level subledgers, and recurring close. Substantial trading activity alone does not establish trade-or-business status.

How is prediction-market income characterized for U.S. federal tax purposes?

There is no single federal tax characterization that applies to every prediction-market contract. Depending on the contract terms, transaction mechanics, and taxpayer facts, the analysis may involve capital or ordinary treatment, wagering rules under §165(d), potential §1256 treatment, §§1234 and 1234A, trade-or-business considerations, and other provisions.

The analysis should distinguish contracts sold or offset before resolution from positions held to an outcome where those facts affect the tax treatment. The venue name alone does not decide the result.

Does Section 1256 automatically apply to contracts traded on Kalshi or another regulated venue?

No. A venue's regulatory status does not, by itself, establish §1256 treatment. The particular contract must satisfy the statutory requirements for an applicable §1256 category, including any relevant exclusions.

We assess the actual contract and applicable law rather than assuming all event contracts on a regulated venue receive the same treatment.

Are prediction-market contracts gambling or wagering transactions for federal tax purposes?

The answer depends on the contract and relevant facts. Prediction-market contracts should not automatically be classified as wagering or non-wagering solely because they trade on a particular platform or carry a particular regulatory label.

Whether §165(d) applies can materially affect loss treatment and reporting. We evaluate the relevant statutory frameworks and document supportable positions based on the underlying activity.

Why does prediction-market accounting matter to the tax analysis?

Tax characterization often depends on facts established by the trading records, including the contracts traded, executions, position changes, sales or offsets, resolutions, fees, rebates, incentives, and amounts paid or received.

If those records are incomplete or unreconciled, the taxpayer may lack a reliable basis for calculating and supporting amounts on the return. For businesses, the same records may also feed the general ledger, financial reporting, and book-to-tax workpapers.

What records should a prediction-market trader or firm maintain?

Keep available trading exports and source records identifying contracts, fills, order or execution details, position histories, sales or offsets, outcomes and settlement amounts, fees, rebates, incentives, cash and wallet movements, and relevant venue statements.

Businesses should also retain accounting records and reconciliation workpapers. The necessary level of detail varies with trading activity, available systems, and the tax positions involved; summary platform reports alone may not be sufficient.

Can Camuso CPA work with my existing accountant, tax adviser, or attorney?

Yes. We can provide specialized prediction-market accounting, technical federal tax analysis, or related compliance support alongside an existing CPA, internal finance team, attorney, auditor, or other adviser.

The scope and responsibilities are agreed at the outset so the specialist work can be incorporated into the appropriate accounting records and tax filings.

When should a prediction-market trader or trading firm engage a specialized CPA?

Preferably before substantial trading volume, new venues, complex contracts, material tax positions, or approaching filing deadlines create difficult historical reconstruction and reporting problems.

Common reasons to engage include rapid increases in volume, market making or algorithmic trading, unreconciled records, significant gains or losses, entity formation or ownership changes, outstanding filings, and the need for written federal tax analysis or ongoing accounting.

Floating