Prediction Market Tax Reporting for Traders, Market Makers & Trading Firms

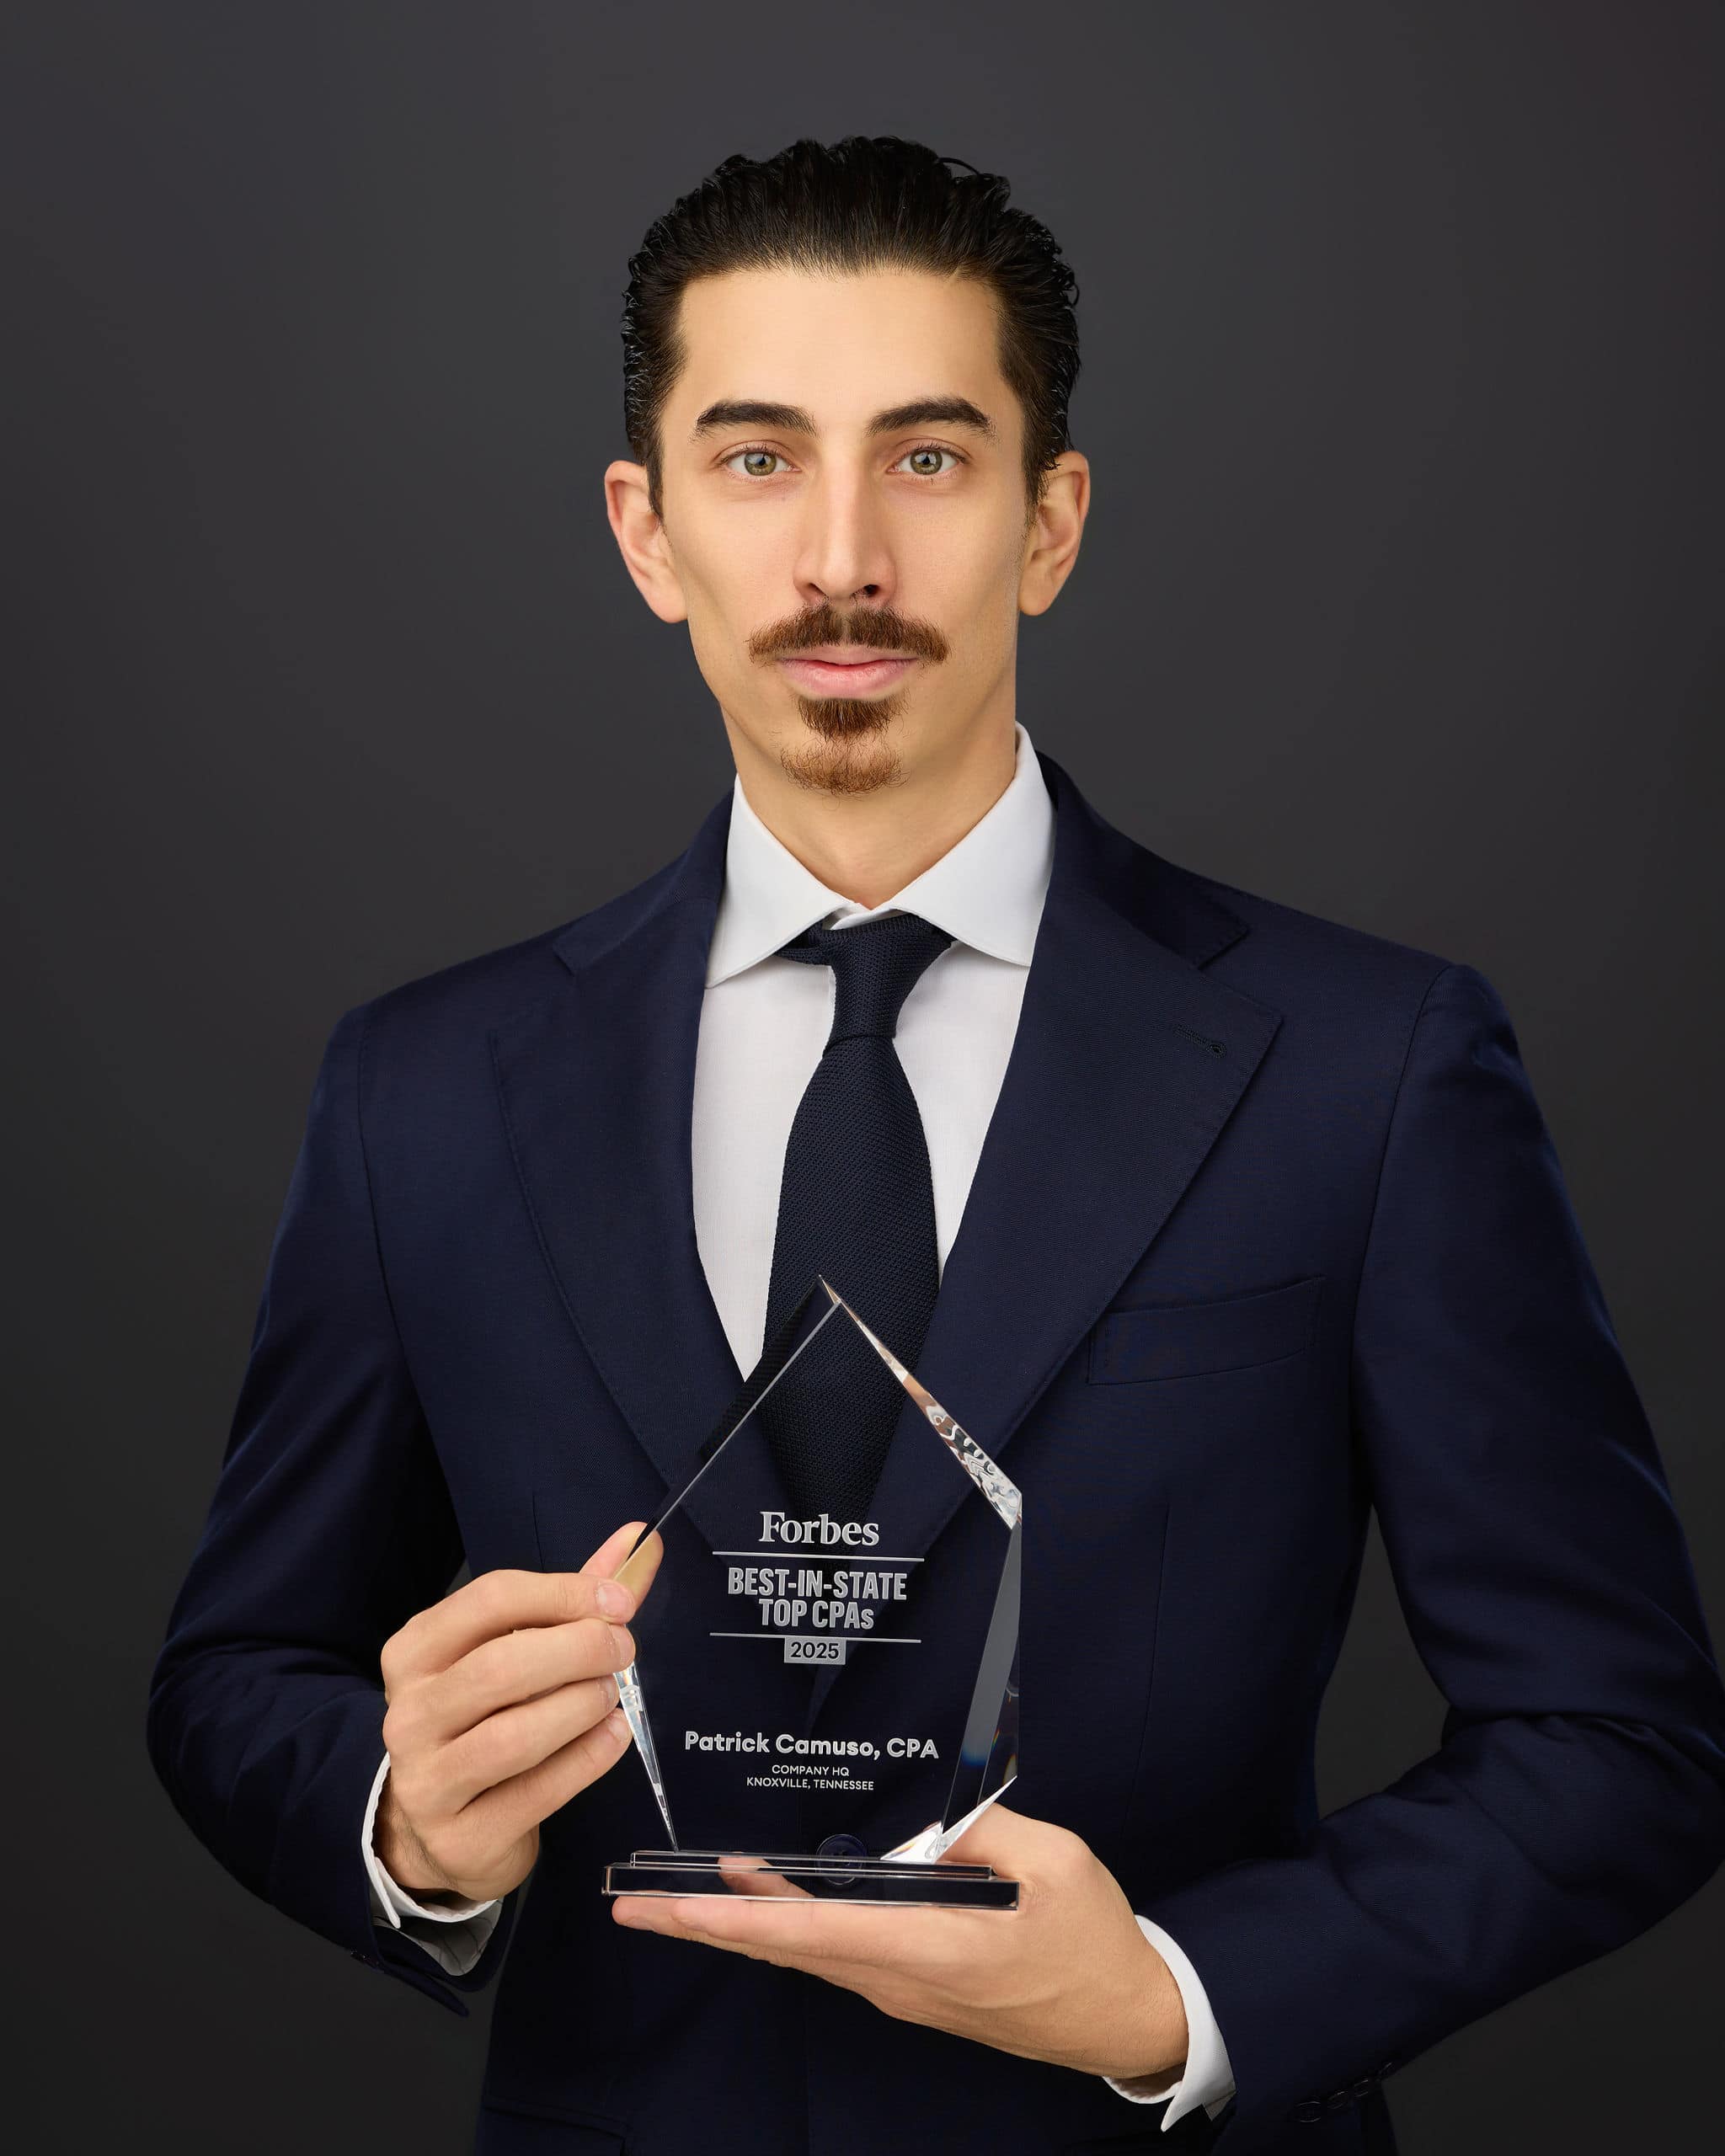
Forbes Best-In-State Top CPA for 2025 and 2026

Featured in Forbes for "Leading the Charge on Crypto Accounting": Read the Forbes Feature

Camuso CPA provides tax analysis, planning, and reporting for prediction-market traders, market makers, funds, and professional trading firms. We analyze the tax treatment of prediction-market contracts, transaction outcomes, trading activity, and related entity and owner reporting, and carry supported positions through the applicable tax workpapers and returns.

Digital-asset accounting and tax practice established in 2016. Dedicated prediction-market tax services for professional trading activity.

Tax Notes
Federal & Global
Published Research

Prediction Market Event Contracts: A Tax Classification Analysis

Co-authored with the former head of the IRS Office of Digital Assets and co-author of the §6045 digital asset broker reporting regulations. A federal tax classification analysis examining how prediction market event contracts may be treated under §165(d) wagering rules, §1256 contract treatment, and general capital or ordinary income rules. Published in Tax Notes Federal and Tax Notes Global.

Read in Tax Notes → Read All Publications →

Prediction Market Tax Reporting Requires More Than Platform Summaries

Prediction-market contracts do not fall under a single federal tax classification simply because they trade on a prediction-market venue. The appropriate treatment can depend on the contract, transaction mechanics, how the position is exited or resolved, the taxpayer’s activity and capacity, and other relevant facts.

Depending on the activity, the federal tax analysis may involve capital or ordinary treatment, wagering rules under §165(d), potential §1256 treatment where the statutory requirements are satisfied, trade-or-business considerations, and entity or owner reporting.

The underlying records matter as much as the legal analysis. Professional traders and trading firms may need to reconcile contract acquisitions and dispositions, resolutions, open positions, fees, rebates, incentives, cash activity, and other transaction data before the tax treatment can be applied consistently to the relevant activity.

Camuso CPA works from the underlying trading records through federal tax analysis, book-to-tax workpapers, and tax reporting. For material or uncertain positions, our work can also include written analysis documenting the authorities, relevant facts, assumptions, and reporting position.

Patrick Camuso | Forbes Best-In-State Top CPA
Patrick Camuso, CPA. Forbes 2025 Best-in-State Top CPA. Featured in Business Insider, Marketwatch, Finops and Morningstar for prediction market tax reporting expertise.

Our Prediction Market Tax Process

Step 1: Trading Activity, Entity & Records Review

We review the taxpayer’s prediction-market activity, venues, contract types, transaction volume, entity and ownership structure, available source records, existing accounting, and prior reporting. This establishes the scope of the tax work and identifies material classification, filing, or documentation issues requiring further analysis.

Step 2: Federal Tax Characterization & Position Analysis

We analyze the tax treatment of the relevant prediction-market activity based on the contracts, transaction mechanics, taxpayer capacity, and applicable authorities. Depending on the facts, the analysis may consider capital or ordinary treatment, wagering rules, potential §1256 treatment, trade-or-business issues, and other federal tax provisions.

Step 3: Tax Reporting & Book-to-Tax Integration

We translate the supported treatment into the applicable tax workpapers and reporting. Where the taxpayer operates through a partnership, corporation, or other entity, we also coordinate the prediction-market activity with the entity and owner reporting required for the engagement.

Step 4: Written Support & Ongoing Tax Planning

For material or uncertain positions, we can prepare written tax analysis documenting the relevant facts, authorities, assumptions, and treatment adopted. Recurring engagements may also include estimated-tax projections, year-end planning, elections, and updates as the firm adds venues, strategies, contracts, or entities.

Prefer to book a time directly?

Prefer to reach us directly? Email info@camusocpa.com or call (704) 249-3179.

Who We Help: Prediction Market Traders, Market Makers & Trading Firms

Camuso CPA works with professional prediction-market participants whose transaction volume, strategies, entity structure, or tax positions require more than ordinary investment reporting.

Our clients include individual professional traders and founder-led trading firms as well as market makers, funds, and other businesses operating across Kalshi, Polymarket, and other prediction-market venues.

Common Prediction Market Tax Issues We Address

Patrick Camuso, Forbes 2025 Best-in-State Top CPA was featured in Forbes for leading the charge on crypto accounting
Patrick Camuso, CPA. Featured in Forbes for Leading the Charge on Crypto Accounting.

Need Prediction Market Tax Analysis or Reporting?

Prediction Market Tax Services

Tax analysis, planning, and compliance for prediction-market traders, market makers, funds, and professional trading firms.

Prediction Market Tax Reporting & Compliance

Federal and state tax reporting for prediction-market activity, including the workpapers required to carry supported contract and transaction treatment into individual, partnership, or corporate tax returns.

Federal Tax Analysis & Written Positions

Technical analysis of material or uncertain prediction-market tax issues, including contract characterization, transaction treatment, §1256, wagering considerations, trade-or-business issues, and other relevant federal tax provisions, with written support where appropriate.

Tax Planning, Elections & Estimated Taxes

Year-round tax planning for professional prediction-market activity, including estimated-tax projections, entity and owner considerations, available elections, changes in trading activity, and year-end planning.

Accounting & Book-to-Tax Support

Where tax reporting depends on incomplete or unreconciled records, Camuso CPA can also provide transaction reconstruction, reconciliation, subledger accounting, general-ledger integration, and book-to-tax support for prediction-market activity.

Why Prediction Market Traders & Firms Work With Camuso CPA

Prediction-market tax reporting can require more than transferring platform totals onto a return. Material activity may require analysis of the contracts traded, how positions were entered and exited, transaction endpoints, taxpayer capacity, and how the underlying activity is reflected in the accounting records.

Camuso CPA combines prediction-market tax analysis with the accounting and transaction-record experience required to implement the resulting treatment. Our work can extend from reconciliation and book-to-tax workpapers through written federal tax analysis, planning, and preparation of the related entity and owner tax returns.

Service Camuso CPA General CPA / Accounting Firm
Prediction-market tax reporting Varies
Contract and transaction tax analysis Varies
Capital, ordinary, wagering and Section 1256 analysis Limited
Multi-venue tax reporting and reconciliation Varies
Written federal tax-position support Limited
Book-to-tax workpapers for prediction-market activity Varies
Prediction-market accounting coordination Varies
Partnership and corporate tax returns
High-net-worth individual tax returns
Prediction Market Tax

Case Study

High-Volume Prediction-Market Trader — Federal Tax Characterization & Reporting

Client Type High-Income Professional Trader
Activity High-Volume Prediction-Market Trading
Annual Volume $2.1M
Focus Federal Tax Analysis & Reporting

The Problem

The client had substantial prediction-market activity across hundreds of transactions but no documented federal tax position addressing how the relevant contracts and transaction outcomes should be reported. The existing trading records also needed to be reconciled before the tax analysis could be applied consistently to the full activity.

What We Did

Camuso CPA reviewed the contracts, transaction mechanics, trading records, and relevant federal tax authorities; evaluated the potentially applicable tax frameworks; reconciled the activity required for reporting; and prepared written support for the treatment adopted in the tax workpapers and return.

The Outcome

The client entered the filing process with reconciled prediction-market activity, a documented federal tax position, and consistent reporting workpapers supporting the treatment applied across the relevant contract population.
Prediction Market Tax Guides & Technical Analysis

Camuso CPA publishes technical analysis on the federal tax treatment and reporting of prediction-market activity. These resources address contract characterization, transaction timing, §1256, wagering considerations, professional trading activity, platform reporting, and related accounting and substantiation issues.

Prediction Market Taxes Explained: How U.S. Tax Law Applie
Kalshi Tax Reporting: What Your 1099 Leaves Out

Section 1256 and Prediction Markets: Do Kalshi and Event Contracts Qualify?

Get Your Prediction Market Tax Reporting Right

Camuso CPA helps professional prediction-market traders and trading firms analyze federal tax treatment, reconcile the records required for reporting, document material positions, and carry the supported treatment through the applicable tax workpapers and returns.

Prediction Market Tax Reporting FAQ

There is no single reporting treatment that applies to all prediction-market activity. The analysis can depend on the contract, transaction mechanics, how the position is exited or resolved, taxpayer capacity, and other relevant facts. Depending on the activity, potentially relevant frameworks may include capital or ordinary treatment, wagering rules, §1256 where the statutory requirements are satisfied, and other federal tax provisions.


Not automatically. Whether wagering rules apply is a federal tax characterization question that depends on the relevant facts and authorities rather than the commercial label attached to the activity. If §165(d) applies, the wagering rules can materially affect the treatment of losses and therefore should be analyzed rather than assumed.

Potentially, but §1256 does not apply merely because a contract trades on a regulated venue. The contract must fall within one of the categories specified by §1256 and satisfy the applicable statutory requirements. Prediction-market contracts therefore require instrument- and transaction-specific analysis before §1256 treatment is adopted.

Not necessarily. Platform records are important source documents, but they do not independently determine federal tax characterization. Depending on the venue and quality of the records, tax reporting may require reconciliation of transactions, dispositions, resolutions, fees, incentives, cash activity, and other data before the applicable tax treatment can be implemented.


It can. The transaction endpoint and mechanics may be relevant to determining the applicable federal tax treatment. A sale or other disposition before resolution should not automatically be assumed to have the same tax consequences as a contract held through resolution, expiration, or settlement.

Multi-venue activity may require records from different platforms to be normalized and reconciled before the appropriate tax treatment can be applied. Differences in contract mechanics, data formats, settlement processes, cash or wallet activity, fees, and reporting can make venue-level reconciliation important to the final tax workpapers.

The tax analysis depends on underlying facts established by the accounting and transaction records. Those records may need to identify contracts traded, position changes, transaction endpoints, amounts paid or received, fees, rebates, incentives, and other activity. Where necessary, Camuso CPA can provide both prediction-market accounting and tax services so the book-to-tax workpapers and filed reporting are based on the same underlying records.

The scope depends on the taxpayer and activity. An engagement may include review and reconciliation of trading records, federal tax characterization analysis, tax workpapers, estimated-tax planning, entity and owner reporting, federal and state return preparation, and written tax-position support for material or uncertain issues.

Traders should generally retain available transaction histories, account statements, contract records, settlement or resolution information, cash and wallet activity, fees, rebates, incentives, tax forms, and other source records relevant to the activity reported on the return. For material positions, retaining information about the relevant contract terms and transaction mechanics may also be important.


A prior return should first be reviewed to determine what was reported, how the underlying activity was calculated, and whether a material reporting error actually occurred. If correction is required, the appropriate approach depends on the facts, amounts, tax years involved, and applicable procedural rules. An amended return should not be assumed to be necessary until that analysis is completed.

Floating