Perpetual Futures CPA for Professional Traders & Trading Firms

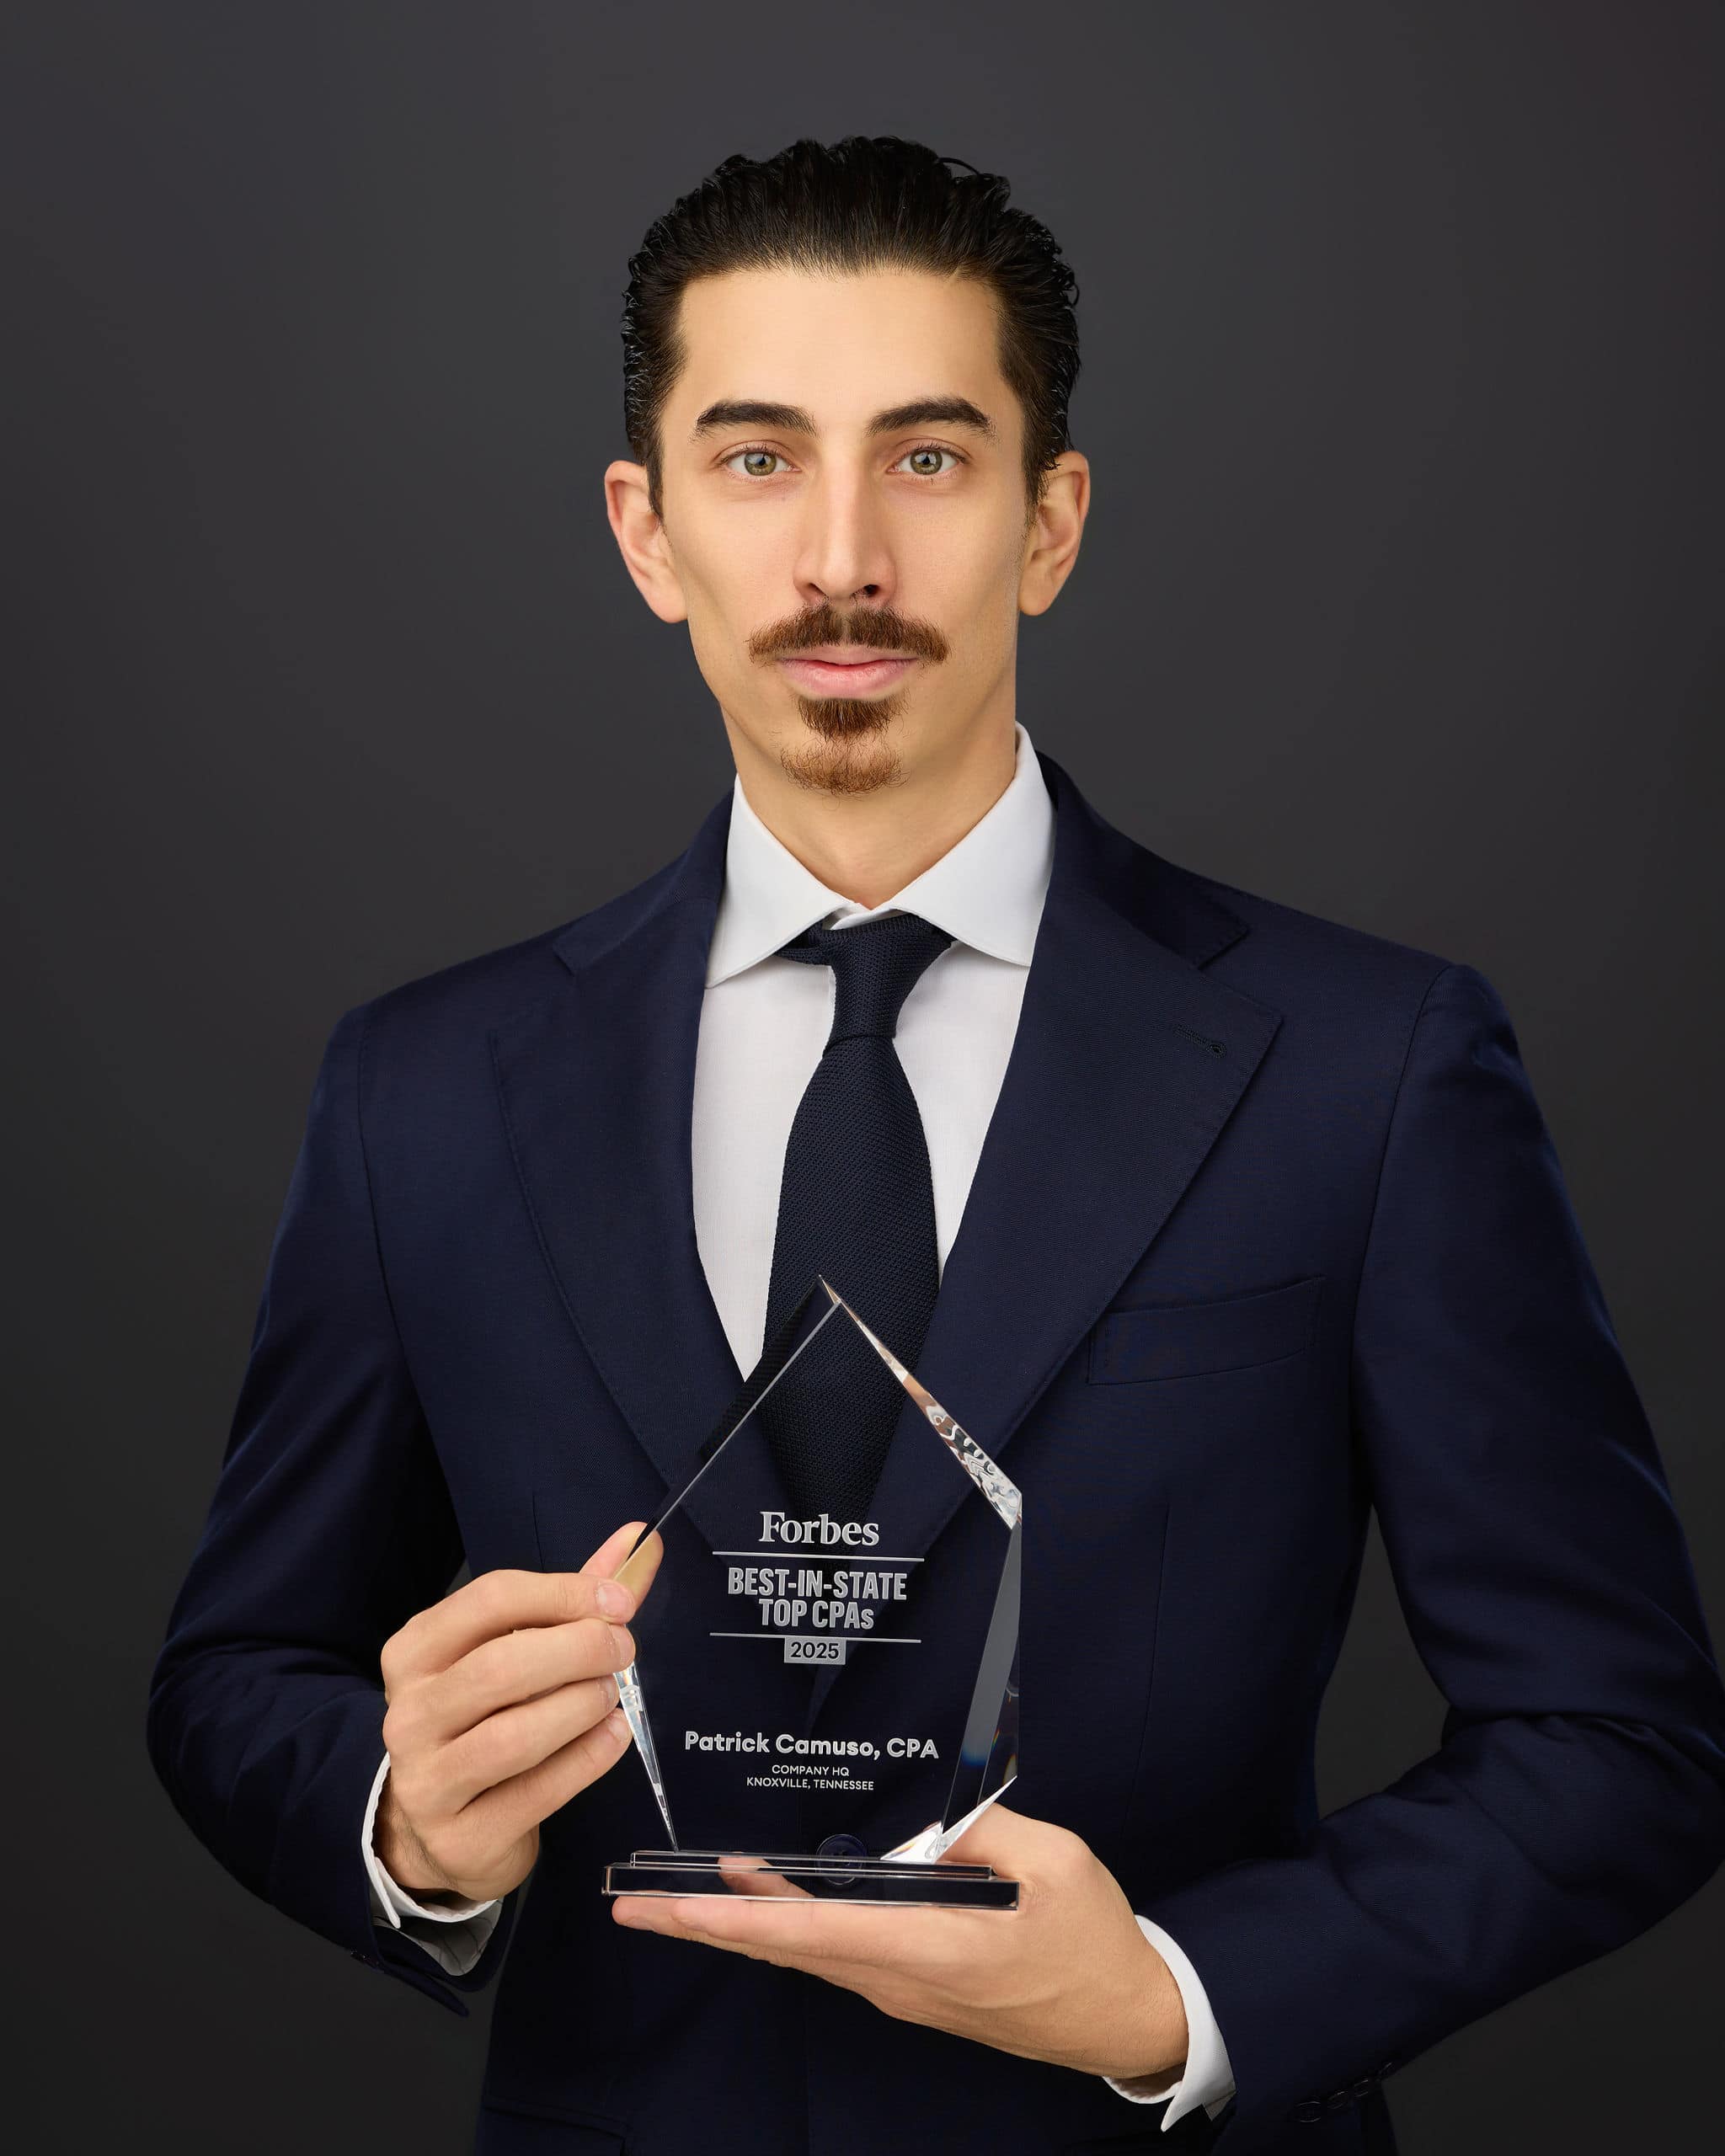
Forbes Best-In-State Top CPA for 2025 and 2026

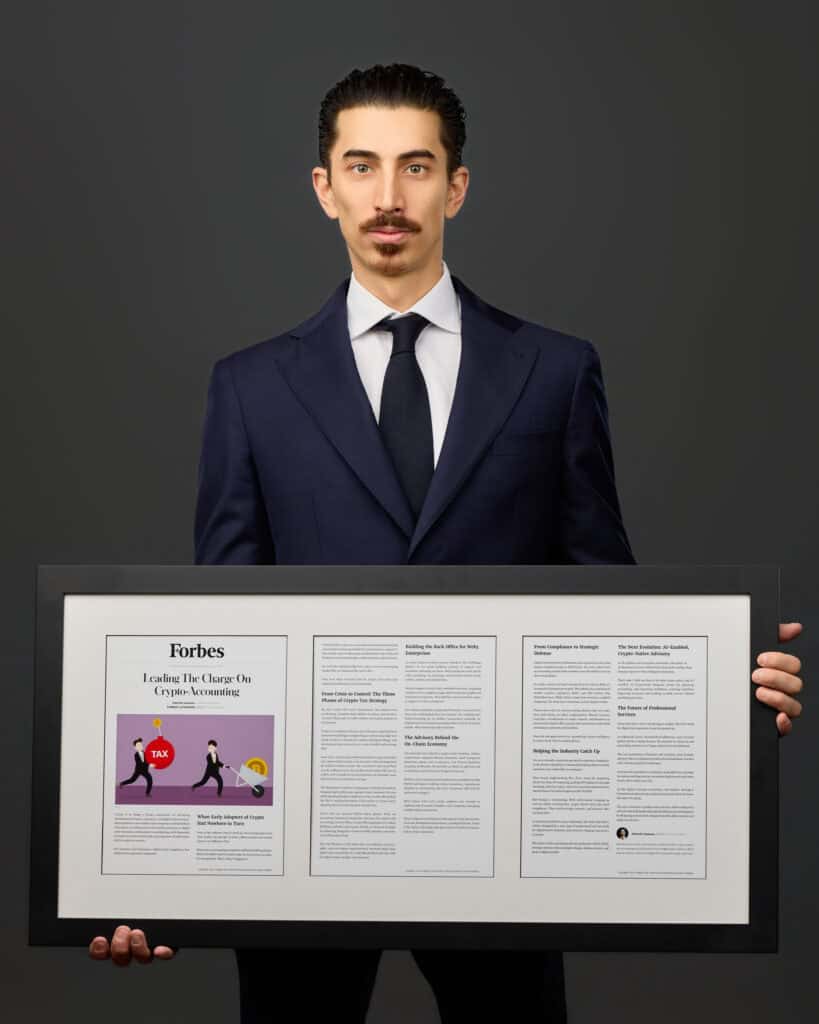
Featured in Forbes for "Leading the Charge on Crypto Accounting": Read the Forbes Feature

Camuso CPA provides specialized accounting and federal tax services for perpetual futures traders, market makers, and trading firms. We help clients reconcile positions, funding payments, collateral and trading activity; analyze complex derivatives tax questions; and establish the records needed for reporting, planning, and compliance.

As Seen In:

Tax Notes
Federal & Global
Published Research

Prediction Market Event Contracts: A Tax Classification Analysis

Co-authored with the former head of the IRS Office of Digital Assets and co-author of the §6045 digital asset broker reporting regulations. A federal tax classification analysis examining how prediction market event contracts may be treated under §165(d) wagering rules, §1256 contract treatment, and general capital or ordinary income rules. Published in Tax Notes Federal and Tax Notes Global.

Read in Tax Notes → Read All Publications →

Perpetual Futures Create Specialized Accounting and Tax Issues

Perpetual futures are derivative contracts that generally allow traders to maintain leveraged exposure without a fixed expiration date. Funding payments, collateral arrangements, partial position closes, liquidations, and venue-specific settlement mechanics create accounting and tax issues that differ from ordinary cryptocurrency spot trading.

Professional traders and trading firms may hold long and short positions across several venues, execute automated strategies, and generate substantial activity through relatively few accounts or wallets. Their transaction histories must distinguish position changes, realized trading results, funding payments, fees, collateral movements, and other events. Exchange statements and trading dashboards may not provide all the information required for complete accounting or defensible tax reporting.

The tax characterization of perpetual futures is not uniform across products and venues. Depending on the contract terms, regulatory structure, transaction mechanics, and taxpayer circumstances, the analysis may involve notional principal contract treatment, capital asset rules, potential Section 1256 treatment, trade-or-business considerations, and available elections. Funding payments and transactions involving cryptocurrency collateral require their own analysis.

Camuso CPA advises individual traders and trading businesses on these issues. Our engagements may involve historical trading reconciliation, specialized accounting, tax-position analysis, planning, return preparation, or recurring financial reporting. Clients can engage us for accounting, tax advisory, or both, based on the nature of their activity and existing records.

Patrick Camuso | Forbes Best-In-State Top CPA
Patrick Camuso, CPA, founder of Camuso CPA and Forbes Best-in-State Top CPA in 2025 and 2026.

Our Perpetual Futures Accounting & Tax Process

Step 1: Contracts, Trading Activity & Records Review

We review the contracts traded, venues, execution and funding history, collateral arrangements, taxpayer or entity structure, prior reporting, and available source records. This establishes the accounting or tax questions that need to be addressed and the appropriate engagement scope.

Step 2: Trading Accounting & Reconciliation

Where accounting support is required, we reconcile positions, trade executions, partial and full closes, funding payments, fees, collateral and cash movements, and other relevant events. For trading businesses, the engagement may also include transaction-level subledger accounting, general-ledger integration, and period-end reporting.

Step 3: Tax Analysis & Planning

We evaluate the applicable federal tax framework based on the actual contract terms and taxpayer facts. Depending on the engagement, our analysis may address income character and timing, funding payments, potential Section 1256 treatment, business versus investment activity, available elections, entity considerations, and material tax positions.

Step 4: Reporting & Ongoing Support

We use the reconciled records and adopted tax positions to prepare applicable tax workpapers and filings. Continuing engagements may include accounting reconciliation, financial reporting, quarterly tax projections, planning, and year-end compliance.

Prefer to book a time directly?

Prefer to reach us directly? Email info@camusocpa.com or call (704) 249-3179.

Who We Help: Perpetual Futures Traders, Market Makers & Trading Firms

Camuso CPA works with individuals and businesses whose prediction-market activity presents complex accounting or federal tax questions. Our clients include high-volume individual traders, algorithmic traders, market makers, proprietary trading firms, and multi-owner trading operations.

Some clients need a technical tax analysis of their contract activity. Others need historical transaction reconstruction, ongoing accounting, financial reporting, or integrated tax compliance. We structure the engagement around the trading activity, reporting obligations, and financial records rather than assuming every trader operates through the same business model.

Ready To Speak With A Prediction Market CPA?

Common Perpetual Futures Accounting & Tax Issues We Address

Patrick Camuso, Forbes 2025 Best-in-State Top CPA was featured in Forbes for leading the charge on crypto accounting
Patrick Camuso, CPA. Featured in Forbes for Leading the Charge on Crypto Accounting.

Perpetual Futures Accounting & Tax Services

Camuso CPA provides accounting, tax advisory, and compliance services for sophisticated prediction market activity. We work with individual professional traders, market makers, and trading businesses, with engagements tailored to their reporting requirements and the complexity of their records.

Perpetual Futures Accounting & Reconciliation

We review and reconcile perpetual futures trading activity, including position histories, realized results, funding payments, fees, collateral, liquidations, and transfers. The work may include historical reconstruction, accounting workpapers, and identifying discrepancies between available venue records and financial activity.

Trading Subledgers & Ongoing Financial Reporting

For trading businesses needing recurring accounting, we help establish reporting processes that connect derivatives activity with the company's books. Scope may include trading subledgers, general-ledger integration, collateral reconciliation, period-end close, and financial reporting based on the data and systems available.

Perpetual Futures Tax Analysis & Compliance

We analyze the federal tax treatment of perpetual contracts and related transactions, including applicable characterization frameworks, recognition and timing questions, funding-payment treatment, and reporting requirements. Our work may include documented tax positions, federal and applicable state tax filings, and coordination with existing advisers.

Tax Planning & Written Tax Positions

We advise on material derivatives tax questions, estimated taxes, trader-versus-investor considerations, entity structure, potential elections, and planning before significant transactions or year-end reporting. Where appropriate, we prepare written analysis grounded in the applicable contracts, facts, and tax authorities.

Why Perpetual Futures Traders Work With Camuso CPA

Perpetual futures accounting requires more than a summary of realized trading profit and loss. Position histories, periodic funding payments, collateral movements, fees, and liquidation events must be understood and reconciled. Where collateral or settlement involves cryptocurrency, separate digital asset transactions may also require analysis.

Camuso CPA has specialized in cryptocurrency accounting and taxation since 2016. Our work with complex digital asset portfolios and professional trading operations includes transaction reconstruction, subledger accounting, financial reporting, and technical federal tax analysis. We apply that experience to the accounting and tax questions arising from perpetual futures and related derivatives.

Patrick Camuso’s research on digital asset taxation has been published in Tax Notes, and his work extends to the federal tax analysis of emerging financial instruments. Camuso CPA also publishes technical analysis of perpetual futures taxation, including the treatment of contract gains and losses, funding payments, and the distinctions between different trading venues and products.

Prediction Market Accounting & Tax

Case Study

Professional Prediction-Market Market Maker — Accounting and Federal Tax Analysis

Client Type Professional Trading Firm
Activity Automated Market Making
Scale Millions of Fills
Focus Accounting, Reconciliation & Federal Tax

The Problem

The firm’s prediction-market activity had reached a transaction volume and level of complexity that required transaction-level accounting beyond platform summaries. The engagement also involved unresolved federal tax issues affecting the treatment and reporting of the firm’s prediction-market activity.

What We Did

Camuso CPA developed transaction-level accounting records and a prediction-market subledger designed to support reconciliation and general-ledger reporting. In parallel, we analyzed the federal tax treatment of the relevant prediction-market activity and documented material reporting positions.

The Outcome

The firm established a coordinated accounting and tax process in which the transaction records supporting the books also provide the factual basis for year-end workpapers and federal tax reporting. The engagement created a consistent connection between the firm’s trading activity, accounting records, and adopted tax positions.

Ready to Speak With a Perpetual Futures CPA?

Prediction Market CPA FAQ

What does a perpetual futures CPA do?

A perpetual futures CPA provides specialized accounting and tax services for traders and businesses operating in perpetual derivatives. The work may include reconstructing position histories, reconciling funding payments and collateral, preparing financial records, analyzing federal tax treatment, planning, and individual or entity tax compliance.

Camuso CPA offers accounting and tax advisory independently or as part of an integrated engagement.

Does Camuso CPA work with individual perps traders and trading firms?

Yes. We advise sophisticated individual traders, owner-operated trading businesses, proprietary trading firms, market makers, and quantitative trading operations.

Individual traders may primarily need tax analysis, reporting, and historical reconciliation. Trading businesses may also require subledger accounting, general-ledger integration, period-end close, and entity tax reporting.

Can you reconstruct historical perpetual futures transactions and provide ongoing accounting?

Yes. We assess the available trading, position, funding, and collateral records to determine the reconstruction or reconciliation work required.

For businesses needing ongoing accounting, engagements may include maintaining reconciled trading records, integrating a derivatives subledger with the general ledger, and supporting recurring financial reporting. The scope depends on the available source data and the trading systems involved.

How are perpetual futures gains and losses taxed in the United States?

The federal tax treatment depends on the actual contract, trading venue, transaction mechanics, and taxpayer facts. Possible frameworks include notional principal contract treatment, capital asset treatment, and Section 1256 treatment where the statutory requirements are satisfied.

Different conclusions can affect income character, recognition timing, loss treatment, and reporting. We analyze the relevant facts and authorities before establishing a tax position.

Do crypto perpetual futures automatically qualify for Section 1256 treatment?

No. The word "futures" does not automatically establish Section 1256 treatment. The analysis includes the relevant statutory contract categories, qualified exchange requirements, potential exclusions, and the instrument's actual terms.

Contracts traded on U.S.-regulated exchanges and perpetual derivatives traded through offshore or decentralized venues may present materially different questions.

How are perpetual futures funding payments treated for tax purposes?

Funding payments must be identified separately from position openings, closes, and other transactions. Their federal tax treatment can depend on the characterization of the underlying contract, the taxpayer's circumstances, and the applicable accounting rules.

We analyze funding received and paid, the timing of recognition, and the treatment of related expenses rather than assuming every payment follows one universal rule.

How are collateral, margin transfers, and liquidations accounted for?

Collateral movements, margin adjustments, position liquidations, and the transfer or disposition of cryptocurrency used for settlement may have different accounting and tax consequences.

We examine the actual asset movements and contract mechanics to distinguish changes in collateral from realized trading activity and any separate digital asset transactions.

What records should a perpetual futures trader maintain?

Traders should retain available execution histories, contract details, position changes, partial and full closes, funding-payment histories, trading fees, liquidation records, collateral deposits and withdrawals, wallet transactions, and venue statements.

Businesses may also need reconciliations and subledger-to-general-ledger workpapers. Summary profit-and-loss reports may not preserve all the information needed to substantiate accounting and tax positions.

Can Camuso CPA work with my existing accountant, tax adviser, or attorney?

Yes. Camuso CPA can provide specialized perpetual futures accounting, historical reconciliation, or federal tax analysis while coordinating with an existing CPA, finance team, tax adviser, or attorney.

The responsibilities and deliverables are agreed at the beginning of the engagement.

When should a perpetual futures trader engage a specialized CPA?

Ideally before substantial trading activity, complex funding arrangements, new venues, significant gains or losses, or approaching filing deadlines make the records difficult to reconcile.

Other common reasons include entering derivatives markets for the first time, forming a trading entity, changing strategies, addressing incomplete historical records, or evaluating a material federal tax position.

Floating