
- Built for Professional Trading Firms in Emerging Markets.
Perpetual Contract Tax Advisory for Professional Traders & Trading Firms
Camuso CPA provides specialized federal tax analysis, planning, and reporting for cryptocurrency perpetual contracts, including perpetual futures and perpetual swaps.
Book a Perpetual Contract Tax Consultation
As Seen In:










Federal & Global
Published Research
Prediction Market Event Contracts: A Tax Classification Analysis
Co-authored with the former head of the IRS Office of Digital Assets and co-author of the §6045 digital asset broker reporting regulations. A federal tax classification analysis examining how prediction market event contracts may be treated under §165(d) wagering rules, §1256 contract treatment, and general capital or ordinary income rules. Published in Tax Notes Federal and Tax Notes Global.
Read in Tax Notes →
Read All Publications →
Perpetual Contract Tax Reporting Requires Instrument Specific Analysis
Often referred to as perpetual futures, perpetual swaps, or perps, these derivatives generally provide ongoing market exposure without a fixed expiration date and use periodic funding mechanisms to maintain pricing relationships with the underlying market.
The appropriate federal tax treatment depends on the contract’s legal and economic characteristics, transaction mechanics, trading venue, and taxpayer circumstances. Depending on the instrument, the analysis may involve notional principal contract rules, capital asset treatment, ordinary income principles, and potential Section 1256 treatment.
A contract does not automatically qualify for mark-to-market and 60/40 treatment merely because it is described as a futures contract. Qualification requires analysis of the relevant statutory categories, exchange requirements, and exclusions for certain swaps and similar agreements. Regulatory classification can inform the analysis without independently determining the federal income tax result.
Funding payments, trading fees, position closures, liquidations, and cryptocurrency-denominated collateral may create additional recognition, characterization, or reporting questions. Transactions involving the underlying digital assets must be distinguished from the derivative contract itself where appropriate.
Camuso CPA evaluates these matters through contract review, technical tax analysis, and the relevant trading records. Engagements may include written federal tax opinions, tax planning, estimated-tax calculations, return preparation, or coordination with existing accountants and attorneys.
Book a Perpetual Contract Tax Consultation
Our Perpetual Contract Tax Advisory Process
Step 1: Trading Activity, Entity & Records Review
We review the perpetual contracts traded, relevant venues, trading histories, funding arrangements, collateral records, taxpayer status, legal entity structure, and prior tax reporting.
Step 2: Federal Tax Characterization & Position Analysis
We analyze the relevant contracts and transactions under applicable federal tax authorities. For material or uncertain issues, we prepare written technical analysis documenting relevant authorities, facts, assumptions, and supported conclusions.
Step 3: Tax Reporting & Book-to-Tax Integration
We apply the adopted tax positions to appropriate reporting workpapers using the available reconciled records. The engagement may include individual, partnership, or corporate returns; owner-level reporting; funding-payment schedules; and coordination with the client’s existing tax or accounting team.
Step 4: Tax Planning, Elections & Ongoing Advisory
For clients engaging us on an ongoing basis, we evaluate anticipated trading results, estimated-tax payments, entity considerations, potentially available elections, and changes in contract or venue exposure.
Prefer to book a time directly?
Book a Perpetual Contract Tax Review Call →
Prefer to reach us directly? Email
info@camusocpa.com
or call
(704) 249-3179.
Who We Help With Perpetual Contract Tax Advisory
Camuso CPA works with sophisticated market participants whose perpetual derivatives activity presents material U.S. tax questions or reporting complexity.
Clients may engage us for a standalone technical opinion, specific planning analysis, tax compliance, or an integrated accounting and tax engagement.
- High-Volume Individual Perpetual Contract Traders
- Proprietary Trading Firms
- Market Makers & Liquidity Providers
- Quantitative & Algorithmic Traders
- Multi-Venue Crypto Derivatives Traders
- Trading Partnerships & Investment Vehicles
Common Perpetual Contract Tax Issues We Address
-
Determining the potential application of notional principal contract rules, capital asset treatment, ordinary income principles, and other federal tax frameworks. -
Evaluating Section 1256 qualification, relevant exchange requirements, statutory swap exclusions, and year-end mark-to-market implications. -
Analyzing funding payments, trading fees, rebates, and incentives for appropriate income or expense treatment and recognition timing. -
Distinguishing position openings, reductions, partial closes, liquidations, settlements, and open positions at the end of a tax year. -
Evaluating margin and collateral movements, cryptocurrency-denominated settlement payments, token conversions, and potential separate digital asset dispositions. -
Assessing trader status, possible Section 475 elections, entity reporting, estimated taxes, and historical filing questions where applicable.
Need a Supported Tax Position for Your Perpetual Contracts?
Book a Perpetual Contract Tax Consultation
Perpetual Contract Tax Advisory Services
Tax analysis, planning, and compliance for perpeutal contract traders, market makers, funds, and professional trading firms.
Federal & State Tax Compliance
Prepare applicable individual or entity returns and supporting schedules using documented tax positions and available trading records. Services may include book-to-tax workpapers, prior-year reporting analysis, and coordination with existing advisers.
Federal Tax Analysis & Written Positions
Evaluate perpetual contract terms, funding mechanics, applicable federal tax rules, income characterization, recognition timing, and material reporting positions. Where appropriate, prepare written analysis supported by the relevant authorities and facts.
Tax Planning, Elections & Estimated Taxes
Evaluate estimated taxes, trading-business considerations, entity structure, and potentially available tax elections. Section 475 eligibility, procedural deadlines, and consequences are assessed based on the relevant taxpayer and instruments.
Accounting & Book-to-Tax Support
Where tax reporting depends on incomplete or unreconciled records, Camuso CPA can also provide transaction reconstruction, reconciliation, subledger accounting, general-ledger integration, and book-to-tax support for perpetual-contract activity.
Why Perpetual Contract Traders Work With Camuso CPA
Perpetual contract tax treatment depends on much more than an exchange’s reported trading profit. Contract terms, funding mechanisms, collateral arrangements, settlement structures, and taxpayer facts can materially affect the federal tax analysis.
Camuso CPA has worked with complex cryptocurrency accounting and taxation since 2016. Our practice combines transaction-level financial analysis, technical federal tax research, and sophisticated individual and business tax compliance.
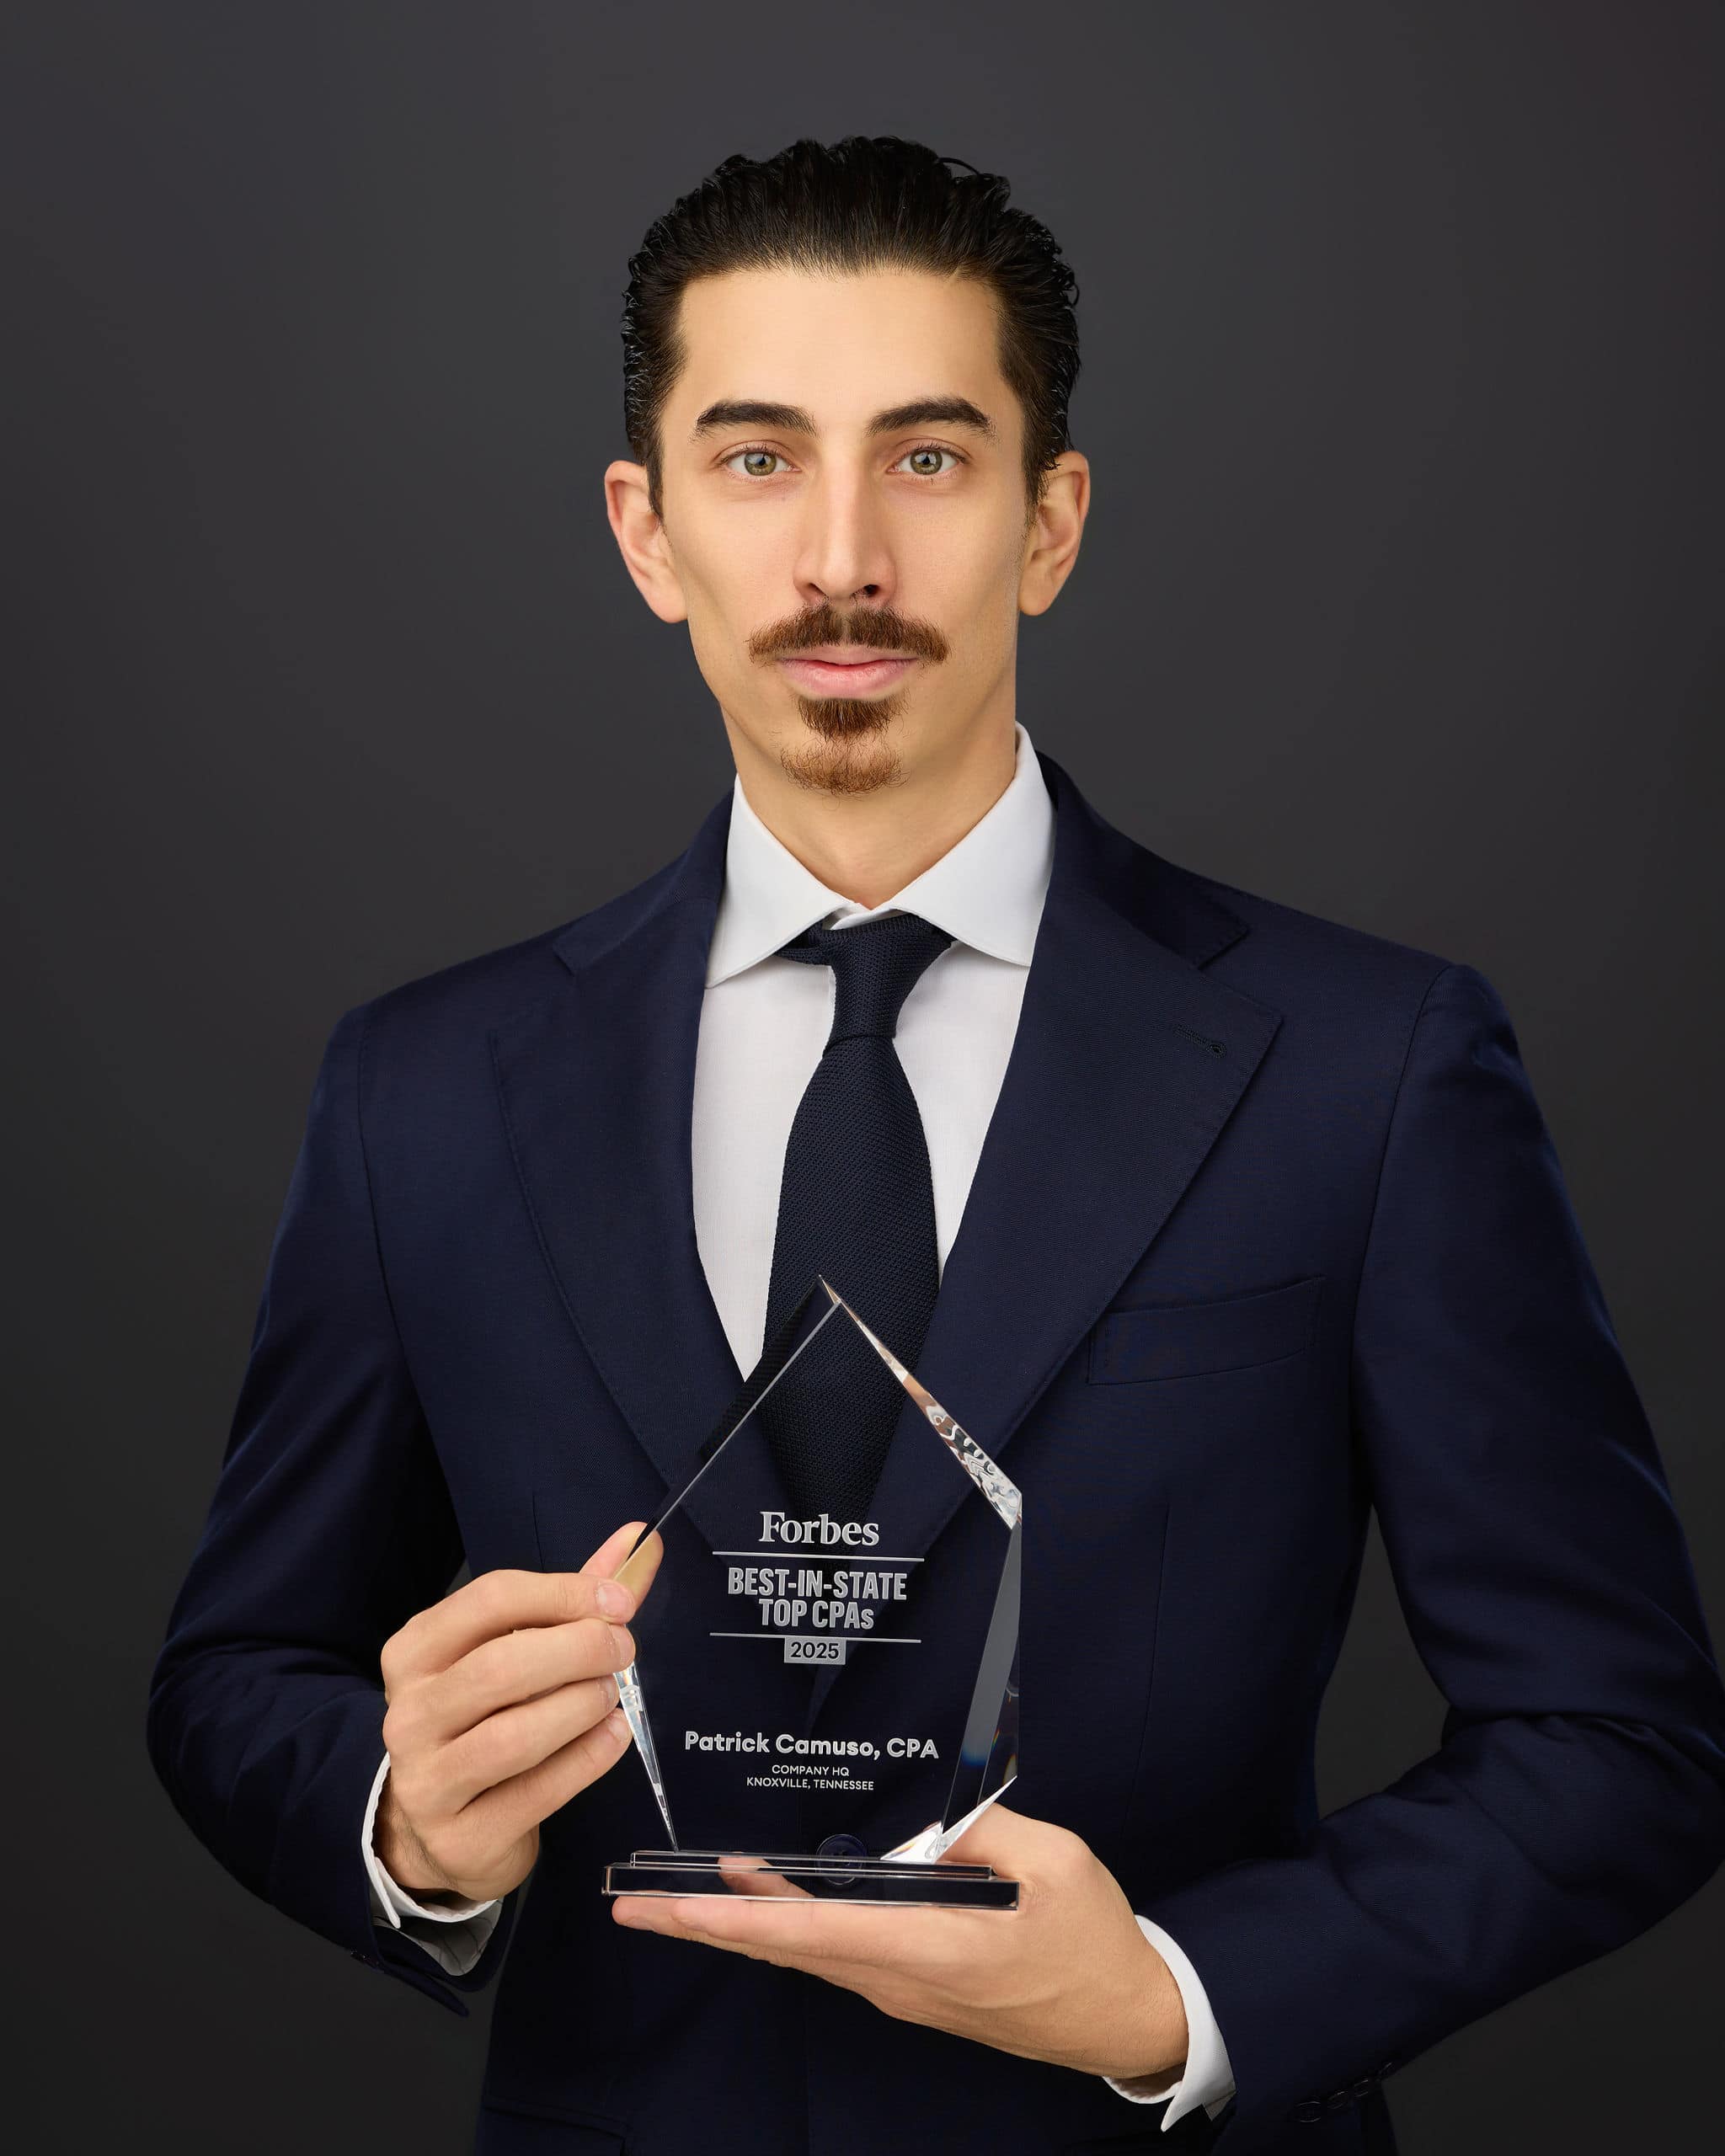
Patrick Camuso, CPA, was selected for Forbes’ Best-in-State Top CPAs lists in both 2025 and 2026. His research on digital asset taxation and other emerging financial instruments has been published in Tax Notes.
Get Your Perpetual Contract Tax Reporting Right
Significant perpetual futures and swaps trading deserves a carefully documented approach to federal tax characterization and compliance.
Book a Perpetual Contract Tax Consultation
Perpetual Contracts Tax Reporting FAQ
How are cryptocurrency perpetual
contracts taxed in the United States?
The federal tax treatment depends on
the contract terms, venue, transaction
mechanics, and taxpayer circumstances.
Potentially relevant frameworks include
notional principal contract treatment,
capital asset rules, ordinary income
principles, and Section 1256 where
applicable statutory requirements
are satisfied.
These distinctions can affect gain
and loss character, recognition timing,
and reporting. Camuso CPA evaluates
the specific instruments and available
authorities before adopting a position.
Do perpetual futures or swaps
automatically qualify for
Section 1256 treatment?
No. The fact that a product is labeled
a perpetual futures contract,
perpetual swap, or regulated derivative
does not automatically establish
Section 1256 treatment.
The analysis includes the statutory
contract categories, qualified exchange
requirements where relevant, and
the exclusion for certain swaps
and similar agreements.
Section 1256 treatment should not
be adopted without reviewing
the actual instrument and
applicable authorities.
Are offshore and decentralized
perpetual contracts taxed differently
from U.S.-regulated contracts?
Different venues and contract structures
may present materially different
tax questions.
Relevant factors can include
contractual terms, regulatory status,
funding arrangements, settlement
mechanics, and counterparty
relationships. Regulatory treatment
does not independently resolve
the federal income tax characterization.
Offshore or decentralized activity
also requires careful recordkeeping.
The absence of an information return
does not eliminate U.S. tax obligations.
How are perpetual contract funding
payments treated for tax purposes?
Funding payments should be identified
separately from position openings,
closes, and other trading transactions.
Their federal tax treatment depends
on the characterization of the
underlying contract, the nature
of the payments, applicable timing
rules, and taxpayer circumstances.
Camuso CPA analyzes funding received
and paid rather than applying one
universal treatment to every
perpetual product.
Do linear and inverse perpetual
contracts create different tax issues?
They can. Linear and inverse contracts
may use different assets for margin,
funding, and settlement.
Coin-margined or cryptocurrency-settled
contracts may require additional
analysis of digital asset valuation,
acquisition costs, holding periods,
and potential separate dispositions.
The applicable treatment depends
on the actual contracts and
settlement mechanics.
Are collateral transfers,
margin movements, and liquidations
taxable events?
Not every collateral or margin
movement automatically creates
a taxable disposition.
The consequences depend on
the contract, ownership rights,
settlement mechanics, and whether
cryptocurrency or another asset
is actually transferred
or disposed of.
Liquidations, fees, and token
conversions can present additional
tax questions that should be
analyzed separately from
the underlying position.
Can active perpetual contract traders
elect Section 475 mark-to-market
treatment?
Potentially, but eligibility
is not automatic.
The analysis includes the taxpayer’s
trading-business status, the nature
of the instruments, applicable
Section 475 provisions, and
the required election and
accounting-method procedures.
Election deadlines and prospective
consequences are important.
Camuso CPA evaluates eligibility
before recommending a position.
What records should I maintain
for perpetual contract tax reporting?
Important records include contract
terms, execution and position
histories, partial closes, funding
payments, fees, rebates, liquidations,
collateral movements, wallet
transactions, and venue statements.
For substantial activity, records
should support the adopted tax
characterization, reconciliation
of amounts reported, and any
separate cryptocurrency transactions.
Summary profit-and-loss reports
may not contain all of the
information needed.
Can Camuso CPA provide a written
tax opinion without taking over
my accounting?
Yes. Camuso CPA can provide
a defined technical tax analysis
or written federal tax position
while coordinating with an
existing CPA, CFO, controller,
or attorney.
If available records do not
adequately establish material
transaction facts, additional
reconciliation may be required.
The responsibilities and
deliverables are agreed
before work begins.
Can Camuso CPA handle tax preparation,
planning, and historical perpetual
contract reporting?
Yes. Depending on the engagement,
services may include written
tax positions, estimated-tax
projections, relevant elections
analysis, individual or entity
returns, prior-year review,
and reporting workpapers.
Historical reconstruction and
ongoing accounting may be included
in a coordinated engagement
or scoped separately.
We review the contracts, trading
history, records, and taxpayer’s
circumstances before establishing
the appropriate services.
Contact Camuso CPA to discuss
your perpetual contract tax needs.
