Last Updated on November 12, 2026 by Patrick Camuso, CPA
Quick Answer
Form 1099-DA is the IRS information return used by digital asset brokers to report certain sales and dispositions. Gross-proceeds reporting began with transactions effected in 2025. For 2026 sales, brokers continue reporting proceeds and must also report basis for covered digital assets, while basis reporting for noncovered digital assets remains voluntary.
A Form 1099-DA is not a complete tax calculation. Historical holdings, transferred-in assets, self-custodied activity, DeFi activity, and other transactions outside the broker’s reporting scope can still require taxpayer-level reconciliation.
Before filing, reconcile the form to the taxpayer’s wallet, exchange, and lot-level accounting records. The objective is to determine what the broker reported, what the taxpayer must report, and whether any difference can be supported from the underlying records.
Form 1099-DA should be treated as an information-reporting input, not as a substitute for the taxpayer’s own basis records.
Common 1099-DA Problems (and why they trigger IRS mismatches)
| Issue | Why It Creates Compliance & Reporting Problems |
|---|---|
| Wallet-by-wallet accounting required | Taxpayers who previously treated all wallets as one pool must reconstruct historical basis by wallet or face IRS recalculation and potential audit exposure. |
| FIFO or Specific Identification only | HIFO, LIFO, and optimized tax-lot strategies are permitted only if executed as valid Specific Identification before each disposal which is something most exchanges cannot support and most taxpayers have never documented. |
| Missing or Incomplete Cost Basis | Brokers cannot compute basis for assets acquired before 2026, transferred in/out, bridged, wrapped, or swapped across chains. Cost basis reporting is delayed, leaving taxpayers responsible for reconstruction. |
| Many taxpayers lack defensible wallet-level documentation | IRS guidance and industry experience indicate that a significant portion of taxpayers do not maintain records aligned with wallet-by-wallet reporting, increasing mismatch risk as broker reporting begins. |
| Certain transactions remain outside current Form 1099-DA broker reporting | Notice 2024-57 currently provides broker-reporting exceptions for specified wrapping and unwrapping transactions, liquidity-provider transactions, staking transactions, digital asset lending transactions, short sales, and notional principal contract transactions. The notice does not determine the substantive federal income tax treatment of those transactions. Taxpayers must analyze the underlying activity under the rules otherwise applicable to it. |
| Transferred-in assets can remain noncovered | A digital asset transferred into a broker is generally a noncovered security for Form 1099-DA basis reporting. A broker may use qualifying customer-provided acquisition information for lot-ordering purposes, but current rules do not permit that information to be used to report the transferred-in asset’s basis or acquisition date as broker-reported basis. |
| Transitional penalty relief does not extend the furnishing deadline | Notice 2024-56 provides limited transitional penalty relief for certain broker reporting failures involving 2025 transactions. The relief is conditioned on a good-faith effort to file and furnish the required information accurately and timely. It does not create a general right for brokers to furnish Forms 1099-DA months or a year after the normal deadline. Any corrected Form 1099-DA received after filing should be reconciled to the filed return. |
| Transaction-date differences require reconciliation | Broker reporting and taxpayer records should be reconciled for transaction dates, settlement mechanics, and other timing differences. A date difference should be investigated from the underlying records rather than assumed to create an IRS notice. |
| Non-custodial DeFi activity generally outside current broker reporting | Many non-custodial protocols do not currently issue Forms 1099-DA, leaving taxable activity outside broker reporting and requiring taxpayer-level reconciliation. |
| Form 1099-DA creates standardized third-party reporting | The IRS now receives standardized digital-asset information from covered brokers. A difference between broker reporting and the tax return can create a reconciliation issue, but a difference does not by itself establish that the taxpayer’s return is wrong or that an IRS notice will be issued. |
| Historical reconstruction may be necessary | Activity across multiple exchanges, wallets, chains, or protocols does not by itself require a historical reconstruction. Reconstruction becomes necessary when the available records cannot establish a reliable lot-level inventory, cost basis, holding period, and transfer history across the relevant accounts. |
Form 1099-DA: What It Reports and How to Reconcile It
Form 1099-DA brought digital-asset transactions into the federal broker information-reporting framework under IRC §6045. Reporting began with transactions effected on or after January 1, 2025.
The regime is now in its second phase. Gross-proceeds reporting continues for 2026 transactions. For sales after 2025, brokers must also report basis and related information for digital assets that are covered securities. Basis reporting for noncovered securities remains voluntary.
That distinction matters because the broker form and the taxpayer’s complete tax record are not necessarily the same thing. Form 1099-DA reflects activity and information within the reporting broker’s scope. The taxpayer’s return can also depend on historical acquisitions, transfers, self-custody, off-platform transactions, and tax treatment that the broker does not determine.
The compliance task is therefore reconciliation. Taxpayers should be able to connect the information reported by the broker to the lot-level accounting and underlying records used on the tax return.
What Is Form 1099-DA?
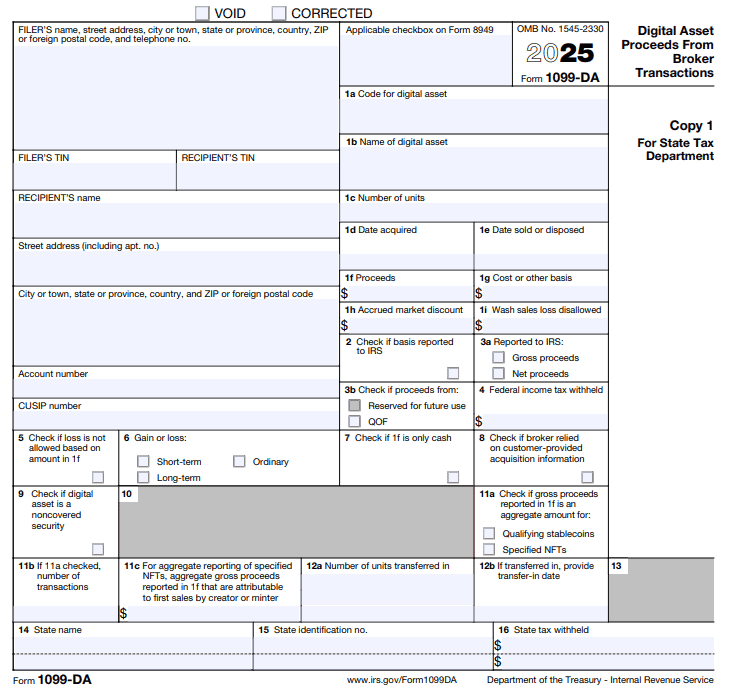
Form 1099-DA, Digital Asset Proceeds From Broker Transactions, is the IRS information return that custodial digital asset brokers must use to report certain digital asset sales and exchanges to both taxpayers and the government, beginning with transactions on or after January 1, 2025. It is the implementation vehicle for the broker reporting rules added to Internal Revenue Code §6045 , the Treasury and IRS issued final digital-asset broker reporting regulations requiring qualifying brokers to begin reporting certain sales and exchanges of digital assets that occur on or after January 1, 2025.
Functionally, 1099-DA does for digital assets what Form 1099-B does for securities, it reports gross proceeds and, for covered positions, basis and related information. It does not calculate the taxpayer’s gain or loss amount. Securities reporting assumes continuous custody and uninterrupted basis tracking. Digital assets do not. Assets routinely move across wallets, chains, and protocols, severing the data lineage brokers would need to calculate basis with confidence. This distinction is the source of nearly every compliance problem investors face under the new regime. For the 2025 tax year, brokers are generally required to report gross proceeds only; mandatory basis reporting is phased in starting with covered digital assets acquired on or after January 1, 2026. Navigating these gaps requires more than software, it requires a crypto CPA who understands how digital asset custody, transfer history, and basis continuity interact across wallets and platforms.
Who is a “Broker” under 1099-DA?
The final regulations clarify that a “digital asset broker” includes any person who, in the ordinary course of business, stands ready to effect sales of digital assets for customers. In practice, this definition includes: centralized exchanges, custodial trading platforms, payment processors that redeem or transfer digital assets, certain hosted-wallet providers, and other custodial intermediaries. A separate December 2024 rule would have extended §6045 reporting to certain noncustodial DeFi front-end participants. Public Law 119-5 disapproved that rule on April 10, 2025, and the disapproved text was subsequently removed from the regulations.
When Treasury issued its proposed digital-asset broker regulations, the definition of a “broker” was broad. It included not only custodial exchanges but also:
- decentralized exchanges (DEXs)
- smart-contract based trading platforms
- AMM and liquidity-pool protocols
- DAO-operated trading interfaces
- wallet software and non-custodial front-ends
This triggered an unusually large comment period and industry response, with significant resistance from the DeFi industry, privacy advocates, digital-rights groups, and even some institutional financial actors.
The final regulations that remain in force apply to a person who, in the ordinary course of business, stands ready to effect sales of digital assets for customers. In the live regime, that is the custodial broker rule already described above. It does not put noncustodial DeFi front-ends back inside broker reporting.
The separate December 2024 rule extending §6045 reporting to certain noncustodial DeFi front-end participants was disapproved by Public Law 119-5 on April 10, 2025 and subsequently removed from the regulations. The IRS confirms that a disapproved rule has no force or effect. That result limits the broker-reporting rule. It does not determine the substantive federal income tax treatment of activity that is absent from Form 1099-DA. Need help filing? Our tax preparation services cover both broker-reported and self-reported activity
What counts as a “digital asset” under 1099-DA?
The regulations define digital assets broadly. Assets that may trigger 1099-DA reporting include cryptocurrencies (Bitcoin, Ethereum, Solana, etc.), stablecoins, non-fungible tokens and fractional NFTs, DeFi and governance tokens, and tokenized real-world assets when handled by a broker. The definition is intentionally expansive. If a custodial broker facilitates the sale or exchange of any cryptographically secured digital representation of value, it falls within scope.
What Form 1099-DA Reports for 2025 and 2026
For transactions effected in 2025, the broker-reporting regime generally required gross-proceeds reporting without mandatory digital-asset basis reporting.
For sales effected after 2025, the rules expand. A digital asset generally qualifies as a covered security when it was acquired after 2025 in an account for which the broker provided custodial services and remained in that account until the broker effected the disposition.
For those covered securities, the broker generally reports both proceeds and basis information.
A digital asset is generally noncovered when it was acquired before 2026, transferred into the broker, acquired outside the broker’s custodial services, or otherwise falls outside the covered-security definition. For noncovered digital assets, basis reporting is voluntary rather than prohibited.
The taxpayer’s basis obligation does not disappear when broker-reported basis is absent. The taxpayer must still determine and substantiate the basis and holding period used on the return.
Qualifying stablecoins and specified NFTs also have special optional reporting methods. When a broker uses an applicable optional method, the information appearing on Form 1099-DA can differ from ordinary transaction-by-transaction covered-security reporting.
Treasury Signals That 2026 Basis Reporting Will Proceed
The 2026 basis-reporting phase should no longer be treated as a tentative implementation date.
In November 2026, Bloomberg Tax reported that a Treasury official said the department has no plans to delay digital-asset basis reporting for brokers another year. That position is consistent with the current Form 1099-DA instructions, which require brokers to report basis for covered digital assets sold after 2025.
The distinction remains important. Mandatory basis reporting applies to covered securities. Noncovered digital assets remain outside the mandatory basis-reporting requirement, although brokers may report noncovered basis voluntarily.
For investors, this means the 2027 filing season will be materially different from the first Form 1099-DA filing season. More 2026 dispositions can arrive with broker-reported basis that must be reconciled against the taxpayer’s own lot-level accounting.
What 1099-DA Does Not (Yet) Cover
Despite its broad new reporting framework, 1099-DA will not capture many common digital-asset events. The IRS itself carved out a range of activities under Notice 2024-57, granting brokers temporary relief from reporting responsibilities for “identified transactions” until further guidance.
- Wrapping and unwrapping transactions
- Liquidity provider transactions
- Staking transactions
- Transactions described as lending of digital assets
- Transactions described as short sales of digital assets
- Notional principal contract transactions
- The form does not cover purely on-chain swaps, smart-contract interactions, AMM trades, staking rewards, or other DeFi-native mechanics when they occur outside a custodial broker environment.
- For 2025 transactions, 1099-DA will generally omit cost basis. It does not calculate the taxpayer’s gain or loss amount.
The absence of a transaction from Form 1099-DA does not determine whether the activity is taxable or how it is taxed. If you participate in DeFi, staking, lending, or noncustodial activity, the return still has to reflect the treatment that applies to the underlying facts.
Why This Matters for Digital Asset Investors
Form 1099-DA creates a new third-party record that has to be reconciled against the taxpayer’s own accounting.
For a covered position acquired and held continuously with the reporting broker, the broker may have the information necessary to report basis. For older positions, transferred-in assets, self-custodied holdings, and activity outside continuous broker custody, the taxpayer’s own records can remain the primary basis support.
This makes historical accounting more important, but it does not mean every multi-wallet investor needs a full reconstruction. Reconstruction is appropriate when the existing records cannot establish reliable basis, holding period, transfer continuity, and remaining lot inventory.
The Three Records Problem: Why Reconciliation Is So Hard
As Patrick Camuso explained in his ETHDenver 2026 presentation on how tax regulation is reshaping Web3, the core challenge for every crypto taxpayer is that you are now dealing with three sets of records that were never designed to reconcile with each other.
Record Set 1: On-chain transactions and exchange records
Your raw activity across blockchains, exchanges, and wallets. This data is not standardized. Each exchange formats exports differently. On-chain data records transfers and swaps but does not record tax-relevant metadata like cost basis, tax lot assignment, jurisdiction, or taxpayer identity. All of that must be constructed through off-chain accounting processes.
Record Set 2: Tax software calculations
The output of whatever crypto tax software or accounting method you use to calculate gains, losses, and income. Different software tools can produce different results for the same activity depending on how they classify transactions, handle DeFi interactions, price thinly-traded assets, and apply accounting methods. There is significant divergence in treatment among taxpayers and practitioners.
Record Set 3: Form 1099-DA
What your broker reports to the IRS. This is the new baseline the IRS uses for automated matching. Your tax return must now reconcile with this third data source, even when the 1099-DA is incomplete or reports transactions differently than your own records show.
The compliance friction comes from forcing these three systems to align. Where they diverge, the IRS flags a discrepancy. Where they align, the filing passes matching without issue. Your job is to ensure alignment or, where alignment is impossible, to document exactly why the records differ and which position is defensible. For additional perspective on how these reporting gaps play out in practice, see our co-authored analysis with Summ: The 1099-DA Stress Test.
The Universal Accounting Method Is Dead for Digital Assets: Mandatory Wallet-by-Wallet Accounting (Effective 1/1/2025)
For years, many taxpayers used the “universal method” of cost-basis tracking by treating all wallets and accounts as a single aggregated pool. Under that approach, taxpayers could select lots across any wallet they controlled, even if the disposal occurred from a different wallet.
Example:
Under the universal method, if a taxpayer sold 1 ETH from a Ledger hardware wallet, they could elect to use a higher-basis lot that originally came from their Kraken account, even though those units never left Kraken. Under wallet-by-wallet accounting, this is no longer allowed. The disposal must be matched only to lots held within the Ledger wallet.
The IRS has formally eliminated the universal method in connection with the new broker-reporting regime under §6045. Digital asset cost basis, holding periods, and tax-lot identification must now be determined wallet-by-wallet or account-by-account.
The Wallet-by-Wallet Requirement (New Mandatory Rule)
Under the post-2024 rules, taxpayers must use lots held in the same wallet or account from which the disposal occurs. Each wallet functions as a separate cost-basis ledger, and lots cannot be mixed across wallets. This shift creates significant tax and operational consequences:
- Each wallet becomes its own accounting silo for basis, holding period, and lot relief.
- Returns filed using the universal method after 1/1/2025 are vulnerable to IRS challenge, adjustments, or exam inquiries.
- Multi-year reconstruction may be required where records are incomplete or where transfers broke historical lot-tracking continuity.
For active traders, multi-chain users, NFT collectors, DeFi participants, and long-term holders who used multiple platforms, this transition is non-trivial and complex.
Rev. Proc. 2024-28: The Transition Safe Harbor
To ease the transition from universal to wallet-by-wallet accounting, the IRS issued Revenue Procedure 2024-28, offering a one-time, elective safe harbor.
Taxpayers could, for transition purposes:
- Allocate unused basis to specific units, or
- Spread remaining basis across a pool of units within each wallet
For most taxpayers, the safe-harbor window has already closed.
If you missed the safe harbor you must still transition to wallet-by-wallet accounting for 2025 onward, but without penalty relief. That means:
- No protection if the IRS disagrees with your prior universal-method application
- No shield from potential adjustments if lot selection was previously inaccurate
This creates a high likelihood of mismatches between taxpayer-reported basis and broker-reported data beginning with 2025 Forms 1099-DA unless the taxpayer proactively transitoins to account based tracking their historical wallet-level basis.
Notice 2026-20 and Lot Identification During 2026
Revenue Procedure 2024-28 addressed the transition of unused basis into the wallet- and account-level system as of January 1, 2025. A separate issue is how taxpayers adequately identify units of digital assets held by a broker when only part of a position is sold, disposed of, or transferred.
Notice 2025-7 provided temporary relief allowing eligible taxpayers to make certain adequate identifications in their own books and records without communicating the identification to the broker. Notice 2026-20 extended that relief through December 31, 2026.
The temporary relief applies to taxpayer lot identification. It does not change the broker’s Form 1099-DA reporting obligations. A taxpayer’s valid identification can therefore produce a different basis result from the broker’s reporting, and that difference must be reconciled and documented.
Under current guidance, the relief ends December 31, 2026. Transactions after that date are subject to the permanent adequate-identification rules unless the IRS publishes additional relief.
Why This Matters: The IRS’s Reporting View Will Not Match the Universal Method
Because brokers will report basis only for covered digital assets they continuously held and because basis reporting for 2025 is limited to gross proceeds, the IRS will begin receiving data structured on an account-specific framework. Any taxpayer still using universal-style aggregation will create structural mismatches between their return and the IRS’s data architecture.
Those mismatches drive:
- CP2000 notices
- underreporting flags
- exam inquiries
- reconstructions upon audit
Given that most taxpayers historically used the universal method, this transition is expected to produce widespread discrepancies unless proactively corrected.
Industry Split: Diverging Interpretations of Wallet-by-Wallet Accounting
Although the elimination of the universal method appears straightforward, practitioners are not unified in how to operationalize “wallet-by-wallet” accounting. The underlying IRS guidance requires cost basis to be determined on a wallet or account basis, but it does not define what constitutes a “wallet” for tax-lot purposes. This ambiguity has produced three major schools of thought within the crypto tax profession.
Below is the landscape as of 2025.
Interpretation #1: Strict Wallet-by-Wallet
Each discrete wallet or account functions as its own independent cost-basis ledger.
- One Metamask address = one wallet
- One Ledger address = one wallet
- One Coinbase account = one wallet
- One CEX sub-account = one wallet
- One cold-storage address = one wallet
This interpretation aligns most closely with:
- Rev. Proc. 2024-28
- The §6045 reporting architecture
- 1099-DA design (per account)
- Covered digital asset rules beginning in 2026
- Transfer statement requirements
- IRS examples and modeling of basis integrity
It is the most defensible position for individuals, investors, founders, and most businesses.
Interpretation #2: Wallet “Batching” or Account Aggregation (Used by Some Practitioners)
Some firms take a looser view and aggregate multiple wallets if they:
- Share the same seed phrase
- Are part of the same Metamask application
- Are the same hardware device with multiple addresses
- Are CEX accounts with multiple sub-ledgers
- Reflect multiple derivation paths
- Belong to the same corporate treasury function
This approach is driven by:
- Software limitations
- Legacy universal-method conditioning
- Pressure to simplify compliance
- Client throughput constraints
- Lack of explicit definition of “wallet” in the regulations
One of the most under-discussed issues in the digital asset reporting regime is that the IRS requires wallet-by-wallet accounting but has never formally defined what a “wallet” is for tax-lot purposes.
This creates significant ambiguity for:
- Bitcoin (UTXO model wallets)
- HD wallets with multiple derivation paths
- Wallet clients that generate dozens or hundreds of addresses automatically
- Multisig wallets
- Smart-contract based wallets
- Enterprise treasury setups with internal routing addresses
- Lightning channels
- State channels and rollup sequencer addresses
- Cold wallets with multiple accounts/paths
- Layer-2 addresses derived from Layer-1 keys
Because the IRS never addressed this technical reality, taxpayers and practitioners must determine what constitutes the actual “unit of account” for basis tracking, a deeply technical question with material tax consequences.
Interpretation #3: Hybrid Approach
A small segment of practitioners use a hybrid model, treating:
- Custodial accounts separately
- But non-custodial wallets grouped
- With exceptions depending on asset flow
- Or using batching only for high-volume, high-friction chains
This introduces inconsistent internal logic, making future audits or IRS data-matching far more complex.
Case Administrative Exception for Complex Entities
Camuso CPA maintains a primary, default position aligned with strict wallet-by-wallet accounting because it is most consistent with:
- The IRS’s technical architecture
- 1099-DA and §6045 broker reporting
- Rev. Proc. 2024-28’s structure
- Audit defensibility
- Basis propagation rules
- Future covered-asset reporting beginning 2026
However, unlike software-driven approaches that apply a rigid rule across all taxpayers, Camuso CPA applies a case-by-case administrative feasibility analysis for large enterprises or highly complex Web3 organizations.
When case-by-case exceptions may be considered:
- Enterprise-level treasuries with hundreds or thousands of addresses
- Protocols or DAOs using smart contract-controlled wallets with multisig fragmentation
- Businesses where addresses represent automated operational functions
- Clients where strict segregation creates a compliance burden disproportionate to IRS reporting capability
- Corporate structures where certain “addresses” represent system-level functions rather than economically distinct assets
Camuso CPA evaluates:
- Materiality
- Actual economic segregation
- Audit risk
- Operational reality
- Alignment with 1099-DA architecture
- Whether batching would distort basis or produce mismatches
- Administrative feasibility under AICPA Statements on Standards for Tax Services (SSTS)
If strict segregation creates distortion or is operationally impossible, we develop a documented, defensible unit-of-account policy for that client, supported by:
Internal memos
- Basis reconciliation maps
- Traceable asset-flow diagrams
- Reconciliation narratives suitable for IRS exam
Why This Matters for 1099-DA Alignment
Brokers will report basis and proceeds per account. The IRS will match data per account.
If a taxpayer aggregates wallets in a way inconsistent with broker-level reporting, they risk:
- CP2000 mismatch notices
- Adjusted gain/loss calculations
- Disallowed losses
- Reconstruction demands during examination
- Penalties for inadequate substantiation
Your approach must match the IRS’s architecture.
Accounting Methods Under 1099-DA: FIFO, Specific ID, and Rev. Proc. 2024-28
The transition framework in Rev. Proc. 2024-28 materially alter how taxpayers may determine tax lots for digital asset dispositions beginning January 1, 2025. These rules interact directly with Treas. Reg. §1.1012-1(c), which governs identification of lots for property subject to capital gain or loss.
For digital assets subject to the specific-identification rules, FIFO generally determines the units disposed of when the taxpayer does not make an adequate and timely identification. Strategies described as HIFO, LIFO, or other lot-ordering conventions do not operate as independent tax accounting methods. They can produce the intended lot order only when implemented through a valid specific identification under the applicable rules. During the Notice 2026-20 relief period, eligible taxpayers can make certain identifications in their own books and records without communicating them to the broker.
This eliminates the long-standing industry practice, prevalent for over a decade, of retroactive or software-generated lot selection, which never satisfied the identification requirements under §1.1012-1(c), even before the new rules. Selecting and documenting the right method before disposal is one of the highest-leverage decisions a crypto investor can make and a core part of cryptocurrency tax planning.
Permissible Methods Under Revenue Procedure 2024-28
FIFO (Default)
FIFO applies whenever a taxpayer fails to make a pre-disposition identification that satisfies:
- §1.1012-1(c)(1) (identification requirements), and
- §1.1012-1(c)(2) (broker confirmation rules, where applicable).
Under §6045 and the final regulations, broker reporting will default to FIFO, and taxpayers must reconcile their records to the broker’s information return absent a valid contrary identification.
Specific Identification
A taxpayer may depart from FIFO only if the taxpayer:
- Identifies the specific unit(s) to be disposed of
- Before the disposition is executed
- With sufficient records to establish
- the acquisition date,
- the cost or other basis, and
- the particular unit disposed of
- Maintains documentation consistent with §1.1012-1(c) and Rev. Proc. 2024-28
- Uses a unit held in the same wallet (or account) from which the disposition occurs
This precludes the practices of:
- Retroactive lot selection
- Software-based “re-optimization” after the fact
- Basis substitution across wallets
- Basis aggregation inconsistent with the functional wallet definition
- Selecting a lot after reconciling CSV files or exchange reports
- Reconstructing “intended” identification post-disposition
Standing Orders as Valid Pre-Disposal Identification (When Properly Structured)
The final regulations reaffirm that a taxpayer may satisfy the pre-disposition identification requirement of Specific Identification by using standing written instructions delivered to a broker or documented in a wallet before any relevant sale occurs, provided those instructions:
- Identify the precise lot-selection methodology (e.g., “highest-basis unit,” “lowest-basis unit,” “last-in unit,” etc.);
- Apply exclusively to units held in the same wallet or account from which the disposition will be executed;
- Remain operative at the time of the transaction; and
- Are retained as part of the taxpayer’s permanent records, consistent with §6001.
Broker confirmations are ordinarily required for adequate identification. However, under Notice 2025-7’s transitional relief, standing orders may function as adequate identification during 2025 even where broker confirmations are not available, so long as the taxpayer’s records demonstrate pre-trade intent and the identification corresponds to the specific wallet/account involved.
In other words, a taxpayer may use HIFO, LIFO, or any optimized variant of Specific ID if they enter a compliant standing instruction before the sale and the instruction exclusively governs that wallet or account. This is the only practical path for most taxpayers to use a non-FIFO method under the post-2024 regime.
A defensible standing order must include:
- Identification Method: The exact rule governing lot selection (e.g., “sell the unit with the highest cost basis in this account,” or “sell the unit acquired last”).
- Wallet/Account Scope: A statement specifying which wallet/account the order applies to.
- Pre-Disposition Timing: The date the order was adopted, which must precede every covered sale.
- Revocation/Modification Protocol:A mechanism documenting changes, ensuring the taxpayer cannot “backdate intent.”
- Record Retention: The taxpayer must permanently retain the written instruction and any subsequent modifications.
This creates a continuous pre-trade identification framework that satisfies §1.1012-1(c) without requiring per-trade manual identification.
Standing instructions must be:
- Prospective, not retrospective,
- Lot-specific by rule, not by reconstruction, and
- Aligned with lots actually held in the wallet at the time of sale.
They cannot:
- Justify after-the-fact “best lot” selection
- Pull units from other wallets
- Override discrepancies between taxpayer records and broker §6045 reporting
- Function as a “catch-all” to cover misidentified or missing lots
This is where most “HIFO software” and post-trade optimization engines fail. Standing orders must govern the sale at the time of execution, not merely describe a desired tax outcome after the fact.
Camuso CPA’s Position Since 2016
Our firm has consistently taken the position that:
- Specific ID must be pre-disposition
- Post-trade “cherry-picking” was never valid under §1.1012-1(c)
Rev. Proc. 2024-28 confirm that this methodology is the correct interpretation.
Why Your Form 1099-DA May Be Missing Cost Basis
Missing basis does not necessarily mean the broker made an error.
For 2026 sales, mandatory basis reporting applies to covered digital assets. A digital asset acquired before 2026 is generally noncovered. A digital asset transferred into the broker is also generally noncovered. Basis reporting for those noncovered positions is voluntary.
This distinction creates several possible outcomes. A Form 1099-DA may show mandatory basis for a covered lot, optional basis for a noncovered lot, or no broker-reported basis for a noncovered lot.
Transferred-in assets present a particularly important limitation. Current IRS guidance permits a broker to consider reasonably reliable customer-provided acquisition information for determining which units were sold. That information cannot currently be used by the broker to establish reportable basis or acquisition dates for the transferred-in units.
The taxpayer therefore remains responsible for maintaining the records necessary to substantiate the basis used on the return.
Historical reconstruction becomes necessary when those records cannot establish the acquisition history, transfers, prior dispositions, and remaining lots that affect the current sale. It is not required merely because the taxpayer used multiple wallets or exchanges.
Transferred-In Digital Assets and Broker-Reported Basis
A digital asset transferred into the reporting broker is generally treated as a noncovered security for Form 1099-DA purposes.
Current IRS guidance allows a broker to use reasonably reliable customer-provided acquisition information for lot-ordering purposes. For example, acquisition information from a transferring broker can help identify which units the customer directed the receiving broker to sell.
That information cannot currently be used by the receiving broker to report the transferred-in units’ basis or acquisition date as broker-reported basis on Form 1099-DA.
The taxpayer may therefore have valid historical basis records even when the broker form does not report that basis. That is a reconciliation issue, not proof that the taxpayer has zero basis.
Example: A Transferred-In Asset With Missing Broker Basis
A taxpayer purchases Bitcoin in 2022, later moves it into self-custody, transfers it to a custodial broker, and sells it in 2026.
The transferred-in Bitcoin is generally noncovered for Form 1099-DA basis reporting. The broker reports the sale and may leave the basis field blank.
The taxpayer’s basis does not become zero because the broker did not report it. The taxpayer must determine and substantiate the basis from the acquisition and transfer records.
If those records are complete, the issue may be resolved through reconciliation. If they are not sufficient to establish the relevant lot history, historical reconstruction may be required.
Not All Digital Asset Activity Appears on Form 1099-DA
Form 1099-DA is not a comprehensive ledger of every digital-asset transaction.
Notice 2024-57 currently provides a broker-reporting exception for specified categories of transactions, including certain wrapping and unwrapping transactions, liquidity-provider transactions, staking transactions, digital asset lending transactions, short sales, and notional principal contract transactions.
The reporting exception is limited to information reporting. Notice 2024-57 expressly does not determine whether an identified transaction is or is not a sale or otherwise establish its substantive federal income tax treatment.
That distinction is important. The absence of a transaction from Form 1099-DA does not determine how the transaction should be treated on the taxpayer’s return. The taxpayer still has to analyze the underlying activity under the substantive rules that apply to it.
The Practical Consequence: Your 1099-DA Will Be Incomplete by Design
A 1099-DA will currently not include:
- DeFi swaps
- LP token minting/burning
- Staking or validator rewards
- Wrapped/bridged asset transformations
- Lending and rehypothecation flows
- NFT mint transactions
- Many NFT sales under $600
- Stablecoin transactions under $10,000
- UTXO reorganizations
- Smart-contract level transfers
- Internal wallet movements
- Airdrops, forks, MEV, rebates, restaking returns
Yet all of these have tax consequences under existing guidance.
This is why relying solely on 1099-DA is a guaranteed path to:
- Underreporting
- IRS mismatch notices
- CP2000 letters
- Examinations
- Multi-year reconstructions
Transitional Penalty Relief Does Not Extend the Form 1099-DA Furnishing Deadline
Notice 2024-56 provided limited transitional penalty relief for certain broker failures during the initial implementation of the digital-asset reporting rules.
The relief was conditioned on a good-faith effort to file and furnish required information correctly and timely. It did not create a general rule allowing brokers to furnish Forms 1099-DA months or a year after the normal furnishing deadline.
A taxpayer who receives a corrected Form 1099-DA after filing should reconcile the corrected information to the filed return and determine whether any further action is necessary.
Transaction Dates and Timing Differences
Digital-asset records can contain different timestamps, settlement information, or transaction dates depending on the source system and the mechanics of the transaction.
Where a broker-reported disposition date differs from the taxpayer’s accounting record, the difference should be traced to the underlying execution and settlement data before the return position is changed.
A timing difference can create a reconciliation issue. It does not by itself establish underreporting or mean that the IRS will issue a notice.
Why DeFi, NFTs, MEV, Bridges, Wrapping, and L2s Are Not Fully Captured by Form 1099-DA
Form 1099-DA reports broker-facilitated dispositions within the broker’s scope. Activity outside that scope can still be taxable. The absence of a form does not determine the treatment. This is why it’s crucial to work with an experienced Crypto CPA.
DeFi: Entire Economies Outside Broker Visibility
1099-DA applies to brokers under §6045.
A separate December 2024 rule would have extended §6045 reporting to certain noncustodial DeFi front-end participants. Public Law 119-5 disapproved that rule on April 10, 2025, and the disapproved text was removed from the regulations. The IRS confirms that the disapproved rule has no force or effect. That result does not determine the tax treatment of activity a broker does not report.
A broker cannot observe:
- LP token minting and burning
- AMM routing paths
- Slippage components
- Internal contract transfers
- Rebase or auto-compounding events
- Yield strategies that restructure basis
- Liquidations and unwinds
- Collateral swaps in lending protocols
- Multi-hop swaps via aggregators
Yet all of these change basis, holding period, character and taxable income.
NFTs: High-Value Assets With Zero Broker Reporting Infrastructure
Many NFT marketplaces might be brokers under §6045, but most transactions occur on-chain, peer-to-peer, or through smart-contract auctions.
Brokers cannot determine:
- Original mint cost
- Gas spent during mint (basis vs expense)
- Secondary-market provenance
- Bundled NFT transactions
- Fractional NFT allocations
Bridges, L2s, and Wrapped Assets: Structural Basis Distortions
Bridging and wrapping often:
- Change token formats
- Create a new token contract
- Destroy and re-mint assets
- Split/merge token IDs
- Trigger events economically equivalent to a disposition + reacquisition
- Occur across chains with different block timestamps
- Lose historical basis if not tracked manually
Brokers cannot see:
- What occurred before the asset arrived on their platform
- Contract-level transformations
- Bridged token metadata
- Wrapped token lineage
- L2 settlement inflows
- Cross-chain canonical vs non-canonical variations
Yet the IRC requires taxpayers to compute gain or loss using cost basis at the unit level.
This creates mismatches between:
- Broker reporting
- Taxpayer reporting
- On-chain economic reality
How Form 1099-DA Information Can Be Used
Form 1099-DA information can be used in information matching. A discrepancy may prompt correspondence or review. It does not mean every difference generates a notice. The form does not establish that the IRS uses any particular machine-learning model, wallet-clustering method, or UTC timestamp convention. We wrote a guide on tax notices related to Form 1099-DA here.
The form reports what the broker reports. Where that information and the return differ, the taxpayer should be able to explain the difference from the records. We can help if you have already received a tax notice from the IRS.
Camuso CPA’s Approach to Form 1099-DA Reconciliation
Form 1099-DA adds standardized broker reporting to an accounting problem that already existed for digital asset investors.
Our approach is to reconcile the broker-reported information to the taxpayer’s complete transaction history rather than treating either the broker form or tax-software output as independently controlling.
That process includes determining which positions are covered and noncovered, reviewing transferred-in assets, identifying historical basis gaps, reconciling lot identification, and separating transactions within broker reporting from activity that remains outside it.
Where the existing records support the tax return, the objective is to document that reconciliation. Where they do not, the historical accounting must be repaired far enough back to establish a defensible current-year result.
State-Level Compliance Under 1099-DA
The arrival of Form 1099-DA does not create a unified national reporting system.
It creates two compliance regimes:
- Federal IRS reporting
- Independent state-level reporting frameworks, each with their own rules, thresholds, and enforcement mechanisms.
States Will Use 1099-DA to Expand Their Own Enforcement
Even though 1099-DA is a federal form, states will use its data to:
- match crypto gains to state returns
- issue missing-return notices
- verify part-year residency claims
- audit high-income crypto taxpayers
- enforce underpayment penalties
- track business withholding obligations
What Camuso CPA Recommends Right Now
For investors, founders, funds, and crypto businesses:
- Treat 1099-DA as a dual-layer system
- Maintain independent wallet-level documentation
- Prepare for inconsistent state thresholds and filing deadlines.
- Track residency carefully, especially if moving between high- and low-tax jurisdictions.
- Monitor state-level guidance monthly, not annually.
Camuso CPA’s advisory practice is already integrating state-level 1099-DA reconciliation into our wallet-level accounting and digital asset compliance reviews. The 1099-DA is not merely a federal requirement. It is also the foundation of a new state-federal enforcement architecture.
Montana is first. Others will follow. And none of them are bound to IRS relief, rules, or interpretations.
Taxpayers and brokers must prepare for a fragmented, multi-jurisdiction reporting environment where:
- federal compliance is necessary but not sufficient, and
- state-level crypto enforcement expands rapidly.
What To Do Now: Tax Planning Before 1099-DA Hits Your Mailbox
Form 1099-DA will not simplify digital asset tax compliance but it will expose every inconsistency between what you report and what brokers report. The taxpayers who suffer the most in 2026 will be the ones who wait until forms arrive. The taxpayers who avoid notices, penalties, and reconstructions will be the ones who prepare now, before 1099-DA goes live.
The actions below are the highest-leverage steps for investors, founders and start-ups preparing for the shift to mandatory wallet-by-wallet accounting, Specific Identification compliance, date differences across records, and broker-data mismatches.
Reconstruct Legacy Cost Basis (2014–2024)
Brokers won’t provide basis for pre-2026 assets or anything moved off-platform.
Reconstruction is essential if you have:
- missing exchange data
- commingled wallets
- DEX activity
- NFT mints or LP tokens without basis
- multi-wallet migrations
This is the foundation of audit readiness. Early year activity that is undocumented is a large risk associated with 1099-DA compliance. Crypto cost basis reconstruction and historical accounting is crucial for overall compliance.
Document Your Transition Under Rev. Proc. 2024-28
You must shift from the universal method to wallet-by-wallet accounting, even if you missed the safe harbor.
This requires:
- a documented transition
- wallet-segmented books
- permanent basis records by wallet
Failing to document the transition increases audit risk.
Re-Engineer Wallet & Account Architecture
Under wallet-by-wallet rules, where you hold a token matters.
Actions to take:
- separate long-term vs. short-term positions
- group high-basis lots intentionally
- ensure Specific ID is feasible in each wallet, as applicable
- align wallets with state residency considerations
This is now a tax-planning process, not just bookkeeping.
Separate Personal and Business Wallets
Mixed-purpose wallets are the fastest path to IRS challenges, especially for founders, operators, and multi-entity structures.
You need:
- clean entity segregation
- treasury vs. personal boundaries
- dedicated business wallets for DAO/protocol activity
Reconcile Dates That Do Not Match
Broker-reported dates and the taxpayer’s other records do not always use the same time convention. A transaction near year-end can appear to fall in different tax years across sources. That is a records-reconciliation issue. The Form 1099-DA instructions do not establish a UTC matching rule.
Conduct a Pre-1099-DA Compliance Audit
Before IRS matching begins, identify and fix:
- missing basis
- mis-segmented wallets
- DEX/DeFi/NFT gaps
- staking/lending/LP misclassification
- state-level exposure
- historical inconsistencies
A pre-1099-DA audit removes future CP2000 surprises.
Set Up Standing Orders for Specific Identification
Where supported, configure standing instructions to ensure Specific ID occurs before execution which is required for HIFO, LIFO, or optimized tax-lot strategies. Most taxpayers and CPAs will fail this requirement. 1099-DA will not fix your records. It will expose them. Taxpayers who prepare now with wallet segmentation, basis reconstruction, Specific ID readiness, and timestamp alignment will be the ones who avoid notices and audits in 2026 and beyond.
Coinbase, Cost Basis, and the Pre–1099-DA Correction Window
Recent updates to Coinbase’s tax infrastructure highlight how quickly crypto tax compliance standards are hardening ahead of Form 1099-DA. Coinbase has confirmed that it will support 1099-DA reporting beginning with 2025 activity, alongside user-selected cost basis methods (FIFO, LIFO, HIFO) and a one-time historical cost basis submission window for correcting missing data. Bulk basis updates are also being introduced.
When 1099-DA reporting goes live, exchange-reported proceeds and basis data will flow directly into IRS matching systems. At that stage, discrepancies are no longer software issues since they become taxpayer substantiation issues, governed by recordkeeping and reconciliation standards. For many investors, 2025 effectively functions as the final correction window before historical assumptions harden into enforcement-grade reporting.
Published Research
Patrick Camuso co-authored a policy analysis of U.S. digital asset taxation in
Tax Notes
alongside the former head of the IRS Office of Digital Assets and co-author of the Section 6045 digital asset broker regulations.
The analysis examines current legislative and regulatory developments affecting digital asset reporting and taxation.
Press Coverage This topic has received coverage from major financial and tax publications:
Further Reading and Expert Commentary
Camuso CPA has produced some of the most referenced analysis in the digital-asset tax field, including policy reviews, technical deep dives, and practitioner-level guidance. For readers who want to understand the full context behind 1099-DA, the transition away from the universal method, and the foundations of modern digital asset complaince, the following resources provide additional depth:
- Podcast with Raj Mukherjee (Former IRS Senior Advisor and CEO of Bodin Advisory)
- Podcast with Miles Fuller (TaxBit, Former IRS Counsel)
- Podcast with Wendy Walker (VP of Regulatory Affairs at Sovos)
- Webinar Entendre on Rev. Proc. 2024-28
- Video: Deep Dive on Cost Basis Reconstruction & Rev. Proc. 2024-28
These materials provide the broader analytical foundation behind the guidance in this report and illustrate why Camuso CPA remains the leading authority on digital-asset taxation and reporting.
Frequently Asked Questions for Form 1099-DA
What is IRS Form 1099-DA and when does it start?
Form 1099-DA is the new IRS information return for reporting digital asset sales and exchanges by custodial brokers. It applies to transactions occurring on or after January 1, 2025, with forms first furnished during the 2026 filing season. It reports gross proceeds and, for covered positions, basis and related information. It does not calculate the taxpayer’s gain or loss amount.
Will Form 1099-DA calculate my crypto gains for me?
No. Form 1099-DA reports gross proceeds and, for covered positions, basis and related information. It does not calculate the taxpayer’s gain or loss amount.
For 2026 sales, Form 1099-DA may report basis for covered digital assets. It can also show no basis for noncovered positions, and special optional reporting rules apply to certain qualifying stablecoins and specified NFTs.
The taxpayer still has to reconcile the form to the taxpayer’s complete records and determine whether any adjustments or additional transactions belong on the return.
What is changing with the universal method and wallet-by-wallet accounting?
The IRS has eliminated the “universal method” you can no longer treat all wallets and accounts as a single basis pool. Beginning in 2025, basis and tax-lot selection must be applied wallet-by-wallet (or account-by-account). Each wallet becomes its own cost-basis ledger and lots cannot be mixed across wallets.
How does Rev. Proc. 2024-28 affect cost basis reporting?
Rev. Proc. 2024-28 provided a one-time transition safe harbor for moving from the universal method to wallet-by-wallet accounting. That window has closed for most taxpayers. Even without the safe harbor, all taxpayers must now transition to wallet-level basis tracking, document the transition, and correct historical basis gaps to align with future 1099-DA reporting.
Which tax-lot methods are allowed now: FIFO, Specific ID, HIFO, LIFO?
For digital assets subject to the specific-identification rules, FIFO generally determines the units disposed of when the taxpayer does not make an adequate and timely identification.
Strategies described as HIFO, LIFO, or other lot-ordering conventions do not operate as independent tax accounting methods. They can produce the intended lot order only when implemented through a valid specific identification under the applicable rules.
During the Notice 2026-20 relief period, eligible taxpayers can make certain identifications in their own books and records without communicating them to the broker.
Why can Form 1099-DA be missing cost basis?
Basis reporting depends on whether the digital asset is covered or noncovered and whether a special optional reporting method applies.
A digital asset acquired before 2026 or transferred into the broker is generally noncovered. Basis reporting for a noncovered security is voluntary.
The absence of broker-reported basis therefore does not establish that the taxpayer has no basis. The taxpayer must substantiate the basis used on the return from the taxpayer’s own records.
Why Is My 1099-DA Inaccurate?
Form 1099-DA frequently appears “wrong” because brokers report only what they can see within their own custodial system. Transfers, bridges, staking, lending, wrapping, DEX activity, and off-platform history break the broker’s chain of custody. The form can also omit categories of transactions that are outside current broker reporting. The form reflects the broker’s limited visibility, not the complete tax picture, and taxpayers must reconcile the gaps independently.
What should I do if my Form 1099-DA does not show cost basis?
First determine whether the asset was covered or noncovered for broker-reporting purposes.
If it was noncovered, missing broker-reported basis may be entirely consistent with the reporting rules. Reconcile the sale to the taxpayer’s acquisition and transfer records and determine the correct basis and holding period.
If the records cannot establish the required lot history, historical cost basis reconstruction may be necessary.
Does 1099-DA report DeFi, NFTs, staking, wrapping, or bridging?
Not necessarily. Notice 2024-57 is a temporary broker-reporting exception for specified wrapping and unwrapping, liquidity-provider, staking, lending, short-sale, and notional principal contract transactions. It does not determine the substantive tax treatment. The separate December 2024 rule extending broker reporting to certain noncustodial DeFi front-end participants was disapproved by Public Law 119-5 and has no force or effect. Absence of an item from Form 1099-DA does not determine whether the activity is taxable.
Does Notice 2024-56 allow brokers to send Form 1099-DA a year late?
No. Notice 2024-56 provided transitional penalty relief conditioned on good-faith compliance. It did not create a general one-year extension of the Form 1099-DA furnishing deadline.
Why can the dates on Form 1099-DA differ from my records?
Digital-asset records can contain different timestamps, settlement information, or transaction dates depending on the source system and the mechanics of the transaction.
Where a broker-reported disposition date differs from the taxpayer’s accounting record, the difference should be traced to the underlying execution and settlement data before the return position is changed.
A timing difference can create a reconciliation issue. It does not by itself establish underreporting or mean that the IRS will issue a notice.
What should taxpayers do before filing a return containing Form 1099-DA activity?
Reconcile each Form 1099-DA to the underlying wallet and exchange records.
- Identify which dispositions involve covered and noncovered assets.
- Confirm the basis and holding period used on the return.
- Review transferred-in positions separately because broker basis reporting may not follow the asset into the receiving account.
- Reconcile any taxpayer-level specific identification to broker reporting.
- Review activity outside the Form 1099-DA reporting regime separately.
- Use historical reconstruction only where the existing records cannot establish a defensible current-year lot inventory.
The Form 1099-DA Reporting Era Is Underway
Form 1099-DA is now an operating part of the federal digital-asset reporting system. The first phase introduced broker-reported gross proceeds for 2025 activity. The second phase adds mandatory basis reporting for covered securities sold after 2025 while preserving different reporting treatment for noncovered assets and certain transactions subject to optional or temporary reporting rules.
The practical consequence is not that every broker form controls the tax return. It is that taxpayers now have another third-party record that must be reconciled to their own accounting.
The strongest filing position is one in which the broker reporting, taxpayer records, basis methodology, and return can be traced to the same underlying transaction history.
It is unlikely that the compliance era stops at Form 1099-DA. The disapproved December 2024 noncustodial DeFi reporting rule is not in force. Form 1099-DA still does not reach every decentralized or self-custodied transaction, and the absence of a form does not determine the tax treatment. As compliance friction from these gaps is felt by taxpayers, practitioners, and the IRS, pressure will build for broader solutions. The probable trajectory is toward integrated on-chain reporting systems where tax-relevant data, including identity, jurisdiction, cost basis, and transaction classification, is captured at the protocol level. This would allow standardized reporting to flow directly from blockchain activity to tax agencies, reducing the reliance on off-chain reconciliation and eliminating many of the mismatch problems that 1099-DA creates.
Related pages for digital asset investors: Crypto Cost Basis Reconstruction Guide.
Related case study: 1099-DA case study.
This article is provided by Camuso CPA for general informational purposes and does not constitute legal, tax, accounting, or investment advice. Tax laws and regulations are evolving rapidly and the information presented may not reflect current guidance. Reading this article does not create a CPA-client relationship. For advice on your specific situation, schedule a consultation with Camuso CPA.
Camuso CPA, PLLC