Last Updated on April 5, 2025 by Patrick Camuso, CPA
Quick Answer
Revenue Procedure 2024-28 provided a transition safe harbor for taxpayers moving from universal or multi-wallet basis practices to wallet- or account-level basis tracking as of January 1, 2025. The procedure addresses how unused basis in digital assets held on that date could be allocated among the taxpayer’s wallets or accounts when its requirements were satisfied.
The January 1, 2025 transition is now historical, but the records created through that transition remain important. Current reporting depends on the taxpayer’s wallet- or account-level lot inventory, and Form 1099-DA now creates a separate broker-reported record that must be reconciled to those records.
This article explains the transition rules, their continuing recordkeeping implications, and the temporary lot-identification relief that followed under Notice 2025-7 and Notice 2026-20.
What Changed After Revenue Procedure 2024-28
The wallet- and account-level digital-asset basis rules became effective beginning January 1, 2025. After the transition, taxpayers still need to maintain lot-level basis and holding-period records within the relevant wallet or account.
For broker-held digital assets, Notice 2025-7 temporarily allowed eligible taxpayers to make certain adequate identifications in their own books and records without communicating those identifications to the broker. Notice 2026-20 extended that relief through December 31, 2026.
The relief does not change the broker’s Form 1099-DA reporting obligations. For 2026 transactions, a taxpayer’s valid identification under Notice 2026-20 can therefore produce a different acquisition date or basis from the amount reported by the broker.
Under current guidance, the temporary relief ends December 31, 2026. Transactions after that date are subject to the permanent adequate-identification rules unless the IRS publishes additional relief.
Key Takeaways
The most important points to understand about Rev Proc 2024 28 include:
- The final regulations require wallet- or account-level basis tracking. Revenue Procedure 2024-28 is the transition safe harbor for allocating unused basis as of January 1, 2025. It does not itself create that wallet-level rule.
- Through December 31, 2026, Notice 2026-20 lets an eligible taxpayer identify broker-held lots in the taxpayer’s own books and records. Outside that relief period, the permanent adequate-identification rules apply unless the IRS issues further relief.
- A safe harbor provision allows taxpayers to allocate unused basis as of January 1, 2025, simplifying the transition from prior practices.
- Allocation methods include specific unit allocation—assigning basis to individual digital asset units—and global allocation, which uses a written rule to allocate basis across wallets.
- Specific-unit allocation is completed before the earlier of the first digital asset sale in the year or the return due date, including extensions. A qualifying global allocation uses a written rule established before January 1, 2025, and the allocation is completed by the later of the first sale or the return due date.
- Starting with the 2025 tax year, brokers will issue Form 1099-DA reporting gross proceeds from digital asset sales.
- Basis reporting by brokers will begin for transactions on or after January 1, 2026.
These changes represent a significant shift in how taxpayers must approach basis tracking and reporting for digital assets. The elimination of the universal accounting method for digital assets poses challenges for taxpayers managing multiple wallets, requiring more detailed tracking and documentation. To reduce administrative burden, taxpayers could consolidate digital assets into one account and manage units of unused basis by December 31, 2024. That date has passed.
Key Changes Under Rev Proc 2024-28
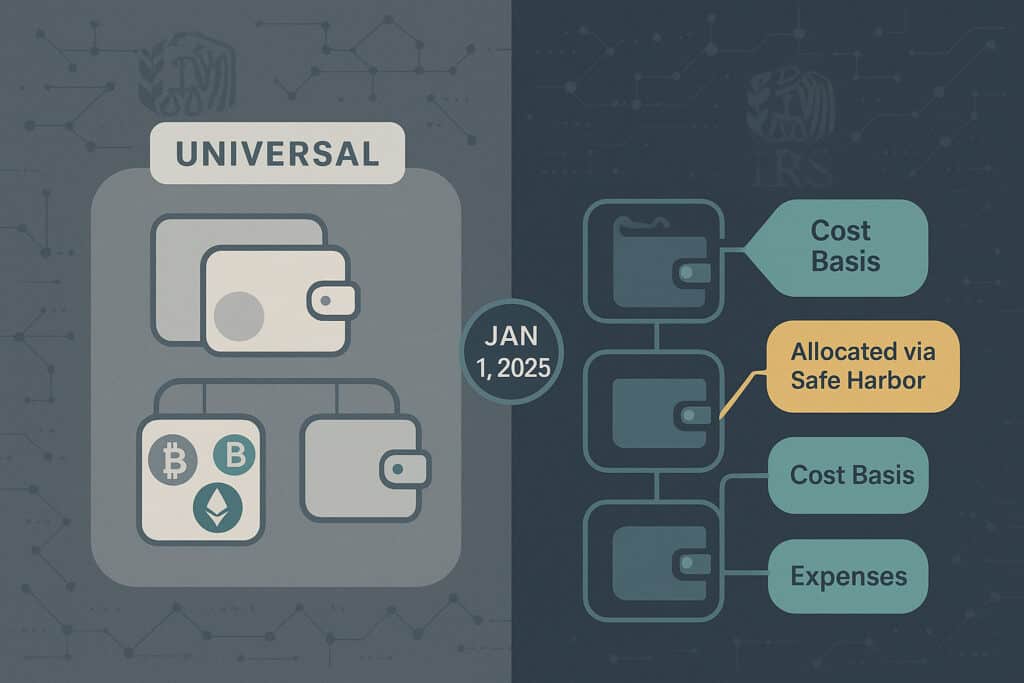
Prior to Rev Proc 2024 28, many taxpayers used a universal method that pooled identical digital asset units from multiple wallets, exchanges, or accounts into a single cost basis pool. This approach allowed flexibility but lacked the granularity the IRS now requires.
The final regulations require lot tracking at the wallet or account level. Revenue Procedure 2024-28 is the transition safe harbor for allocating unused basis as of January 1, 2025. Within a wallet or account, specific identification or FIFO applies under the identification rules. Through December 31, 2026, Notice 2026-20 lets an eligible taxpayer make that identification for broker-held units in the taxpayer’s own books and records. Communicating a standing order to the broker is a permanent-rule question. It is not a requirement of the revenue procedure during the relief period.
To ease the transition relief, Rev Proc 2024 28 provides a safe harbor that allows taxpayers to allocate their remaining unused basis as of January 1, 2025 to each wallet or account holding digital assets. This allocation can be done using either specific unit allocation or a global allocation method. The safe harbor applies only to capital assets held as of January 1, 2025.
Compliance note: The IRS’s final regulations on digital asset lot identification are found in Reg. §1.1012-1(j). Brokers will begin reporting gross proceeds on Form 1099-DA for sales occurring in 2025, and adjusted basis reporting will start in 2026. This means taxpayers must be prepared to track and report basis accurately at the wallet level going forward.
Key Terms in Plain Language
Understanding the following terms is critical guidance for complying with Rev Proc 2024 28:
- Remaining units: These are the digital asset units you still hold in a specific wallet or account as of January 1, 2025.
- Unit of unused basis: The portion of your original cost basis that has not yet been allocated to a sold unit.
- Specific unit allocation: Assigning specific basis amounts to individual remaining digital asset units in each wallet or account, documented in your records.
- Global allocation: A written rule, created before January 1, 2025, that allocates unused basis across wallets or accounts holding the same digital asset.
- Standing order: An ongoing instruction to a broker or an internal rule for selecting which lots to sell, such as FIFO or highest cost first.
These terms help clarify how taxpayers should approach allocating unused basis and tracking digital asset transactions under the new rules.
Deadlines That Matter
Meeting deadlines is crucial to benefit from the safe harbor provisions of Rev Proc 2024 28 for the taxpayer’s digital assets :
- For specific unit allocation, you must complete the allocation before the earlier of your first digital asset sale in the year or your tax return due date, including extensions.
- For global allocation, the written rule must be established before January 1, 2025, and the allocation must be completed by the later of your first sale or tax return due date.
It is important to note the safe harbor applies only to basis and units held as of January 1, 2025 and requires adequate substantiation through your records. Allocating unused basis must be documented clearly to prevent mismatches during income tax reporting and improve IRS compliance.
Failing to meet these deadlines or maintain sufficient documentation removes safe harbor protections, exposing you to potential tax adjustments, penalties, and interest. Failure to follow the new regulations may result in additional tax assessments, penalties, and interest, emphasizing the importance of compliance.
Applying Rev Proc 2024-28 for Digital Asset Basis Allocation
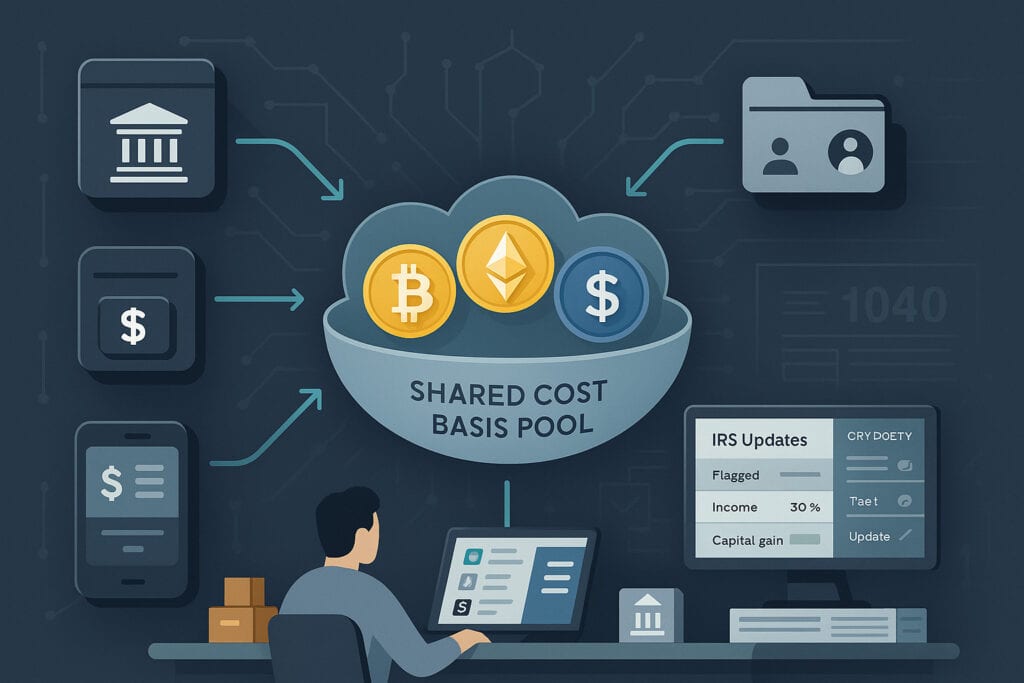
To illustrate the impact of Rev Proc 2024 28, consider this example:
You purchased 1 Bitcoin (BTC) on Kraken for $40,000 and 1 BTC on Coinbase for $60,000 during 2024. As of January 1, 2025, you still hold both units. Later in 2025, you sell 1 BTC from your Coinbase account.
- Under the universal method, you could have used the $60,000 cost basis for the sale regardless of which wallet the BTC was sold from.
- Under the post-2025 rules, you must identify lots at the wallet or account level. Without specific identification, the default FIFO method applies within the Coinbase wallet.
- Using the safe harbor, you can allocate the unused basis as of January 1, 2025, by either specific unit or global allocation to determine which cost basis applies to the sale.
The key takeaway is that you cannot mix basis from Kraken with Coinbase unless you have transfer records showing the lot moved between wallets before the sale.
Standing Orders That Work
To simplify lot identification and ensure compliance, many taxpayers use standing orders. These are pre-established rules or instructions that automatically determine which lots are sold first. Examples include:
- Selling the highest cost per unit first, then by earliest acquisition date, and then by highest total lot cost if there is a tie.
- Applying FIFO within each wallet or account.
- Using specific tax lot IDs based on purchase timestamps and prices, recorded in your ledger.
Record the identification in the taxpayer’s books. Through December 31, 2026, Notice 2026-20 does not require an eligible taxpayer to give that identification to the broker. Outside the relief period, the permanent adequate-identification rules apply unless the IRS issues further relief.
Recordkeeping Checklist
Maintaining sufficient records is essential under the updated rules. For every wallet or account, keep:
- The total remaining digital asset units on January 1, 2025 for each asset.
- For each unit of unused basis: original cost, acquisition date, and source wallet or account.
- A written global allocation rule if you use that method.
- Books and records showing when allocations were completed.
- The books-and-records identification made during the Notice 2026-20 period, or the broker communication required once the permanent rules apply.
- Transfer logs with transaction hashes, from/to addresses, timestamps, and fees.
- Broker statements and CSV exports.
- Annual reconciliation tying ending basis to the next year’s starting basis.
Taxpayers must maintain sufficient records to identify total remaining digital assets in each account by the deadline.
Good recordkeeping reduces administrative burden and ensures audit readiness for basis in digital assets .
Software Setup Tips
Many digital asset users rely on crypto tax softwares to facilitate compliance with Rev Proc 2024 28. To optimize your setup:
- Enable per wallet or account lot tracking.
- Import complete transaction histories, including self-custody and exchange activity.
- Reconcile transfers by matching inbound and outbound records.
- Lock your January 1, 2025 snapshot once reconciled to prevent changes.
- Export an allocation audit file showing your allocation rule and resulting lot mapping.
Taxpayers may use specialized crypto tax software to help automate the allocation of digital assets acquired and unused basis according to new IRS guidelines.
- Enable per wallet or account lot tracking.
- Import complete transaction histories, including self-custody and exchange activity.
- Reconcile transfers by matching inbound and outbound records.
- Lock your January 1, 2025 snapshot once reconciled to prevent changes.
- Export an allocation audit file showing your allocation rule and resulting lot mapping.
Using software that supports wallet-level cost basis tracking is critical to meeting IRS expectations.
Common Pitfalls and Red Flags
Watch out for these common mistakes that can jeopardize your compliance:
- Selling digital assets in 2025 before completing your specific unit allocation.
- Writing a global allocation rule after the January 1, 2025 deadline.
- Allocating basis that has already been used to remaining units.
- Treating an exchange account as a single wallet while mixing in self-custody lots without proper transfer records.
- Using HIFO (highest-in, first-out) without a standing order or timely identification.
Avoiding these pitfalls will help you stay within the IRS’s safe harbor and reduce audit risk.
The End of Pooling: Crypto Is Now Account-Based
Historically, many taxpayers and software platforms used a pooled, global cost basis for crypto treating all wallets and exchange accounts as one. This allowed for post-sale Specific Identification (Spec ID), enabling taxpayers to cherry-pick lots after the fact to reduce gains. But this approach never had strong grounding in the regulations.
Under IRC §1012 and Treas. Reg. §1.1012-1(c)(1), cost basis tracking has always presumed account-based recordkeeping. The final regulations require each wallet or exchange account to be tracked individually. Revenue Procedure 2024-28 is the transition safe harbor, not the source of that rule. The implication is massive: every acquisition and disposal must be traced within its original account. No more merging assets from different wallets to optimize outcomes.
To comply, taxpayers must now treat each account whether an exchange, custodial platform, or self-custodied wallet as a distinct “container” with its own FIFO or Spec ID tracking. Pooling is no longer permissible under the safe harbor.
The Regulatory Backbone: Revenue Procedure 2024-28 vs. Notice 2025-7
IRS Notice 2025-7 provides temporary relief and operational guidance to brokers subject to new digital asset reporting obligations under Section 6045. It outlines acceptable forms of specific identification under the new Form 1099-DA framework.
The final regulations require wallet- or account-level application of basis rules beginning in 2025. Rev. Proc. 2024-28 provides a transition safe harbor for allocating unused basis into that framework. It does not impose the wallet- or account-level rule. Notice 2025-7 addressed broker reporting operations. It is not the source of the basis rule.
Within a wallet or account, FIFO applies when adequate identification is absent. Through December 31, 2026, Notice 2026-20 lets an eligible taxpayer identify broker-held units in the taxpayer’s own books and records.
The final regulations require taxpayers to apply basis rules by wallet or account, including self-custody wallets. Revenue Procedure 2024-28 does not create an exception for self-custody.
Account-Level Tracking Is Mandatory, Including Wallets
IRS guidance now requires wallet-level segregation. Each wallet or custodial account is treated as a discrete repository,akin to a brokerage account under legacy securities law.
This has two implications:
- FIFO must be applied per wallet, unless Spec ID is properly executed.
- Basis tracking tools must maintain segregated ledgers across all wallets and exchanges.
This creates several noncompliance risks including universal pooling, app-based cost aggregation, or cross-wallet Spec ID may all fail IRS scrutiny under audit. Retroactive reallocation is disallowed.
Pre-Sale Specific Identification: Now Required
The old method of post-sale specific identification that included reviewing lots after a transaction and choosing which one to apply is no longer valid.
Under both Rev. Proc. 2024-28 and the historical Treasury Regs:
- Specific identification must be done before or at the time of sale.
- Taxpayers must maintain standing instructions or use transaction metadata that identifies the lot.
Pre-2025 Holdings Must Be Allocated
Any digital assets held before January 1, 2025, must be properly allocated to the wallets or accounts in which they resided. This includes:
- Assigning cost basis to each wallet
- Mapping legacy purchases to their correct wallet or exchange
- Segmenting holdings to reflect actual custody structure
Taxpayers who fail to do this will have no defensible position for applying FIFO or Spec ID on a wallet basis. The IRS will likely impose wallet-level FIFO without regard to actual acquisition history. This is a one-time opportunity to cleanly segment cost basis using historical cost basis data.
Audit Risk and IRS Enforcement Outlook
Under the new regime, the IRS is likely to evaluate basis reporting by:
- Reviewing wallet segregation
- Confirming standing instructions for Spec ID
- Validating timestamps on cost basis identification
Failure to satisfy these standards could result in forced FIFO, disallowance of losses, or gain acceleration.
The IRS has made clear that improper cost basis accounting is a priority enforcement area. The digital asset audit will likely include a review of:
- Cross-wallet basis allocations
- Wallet transfer documentation
- Timing and form of lot identification
- Software-based lot selection algorithms
This isn’t just a paperwork issue. If you’ve been trading actively in 2025, you may have already locked in gains without proper identification. That means the IRS will likely default you to FIFO per wallet/account, even if it dramatically increases your taxable gain. Worse, you may not be aware of this until your return is filed or challenged.
The problem compounds under the new 1099-DA regime. Once brokers begin furnishing these forms to the IRS (expected in 2026 for 2025 activity), there will be complete transparency into your trades. If your reported gains don’t match, or you try to use Spec ID without documentation, you’re at risk for audits, penalties, and additional tax due.
Misinterpretations and Clarifications
Several prominent misinterpretations have circulated, including:
“Notice 2025-7 doesn’t apply to wallets, so Spec ID rules don’t either.”
False. Spec ID rules derive from Rev. Proc. 2024-28 and Treasury Regs, which apply to all taxpayers, regardless of 1099-DA.
“You can use post-sale Spec ID for non-brokered wallets.”
False. Post-sale identification violates the longstanding rules for securities and now for digital assets. Identification must be done pre-sale.
“You can aggregate wallets into a universal pool.”
False. Wallet-level tracking is mandatory. Aggregation violates the procedural requirement of account-based segregation.
“FIFO is only mandatory on exchanges.”
False. FIFO is the default anywhere unless you make pre-sale Spec ID.
Strategic Response: Building an Audit-Defensible Ledger
Crypto investors, funds, and tax professionals must now adapt their infrastructure:
- Use tools that support wallet-level segregation and proper cost basis allocations
- Implement standing instructions for tax-lot realization if using SpecID (LIFO, HIFO, etc.)
- Timestamp Spec ID elections contemporaneously
- Document cross-wallet transfers with supporting metadata
- Allocate pre-2025 assets to correct wallets with defensible audit trails
Most Investors Are Already Out of Compliance
Crypto cost basis rules have quietly but decisively changed. IRS enforcement is no longer hypothetical. Every wallet, every transaction, and every sale must now adhere to account-level segregation and pre-sale identification.
Investors and preparers who continue to rely on post-sale Spec ID or universal pooling are operating on outdated assumptions and may face aggressive audits. The safest path forward is immediate adoption of audit-defensible methods like wallet-level FIFO or standing instruction-based Spec ID. By acting now, especially to allocate pre-2025 holdings, taxpayers can preserve defensible basis, reduce phantom gains, and avoid a compliance crisis in 2026 and beyond.
This is a foundational shift in crypto tax compliance. What used to be an ambiguous area is now governed by clear IRS procedures. Account-level tracking is required. Post-sale Spec ID is dead. Cost basis allocations must be cleaned up now to avoid disaster later.Investors, founders, and funds must act swiftly. Advisors must update workflows. Software vendors must adapt. The window to catch up is shortand enforcement is coming.
Expert POV
Revenue Procedure 2024-28 should now be treated as part of the historical foundation of a taxpayer’s basis records. The current compliance question is whether the wallet- or account-level inventory can be carried forward, reconciled to transfers and dispositions, and supported against broker reporting.
Current Status
Form 1099-DA gross-proceeds reporting began with 2025 transactions. For 2026 sales, brokers must report basis for covered digital assets, while basis reporting for noncovered digital assets remains voluntary.
Notice 2026-20 extends the temporary books-and-records identification relief for eligible broker-held digital assets through December 31, 2026.
Compliance Notes and Disclaimers
This article provides a high-level summary of IRS guidance and is not intended as tax or legal advice. For detailed rules, refer to:
- Rev Proc 2024 28 for safe harbor allocation rules.
- Reg. §1.1012-1(j) for lot identification requirements.
- IRS guidance on Form 1099-DA for sales reporting.
Consult a qualified tax professional to ensure your specific circumstances are addressed.
What Taxpayers Should Do Now
Start with the January 1, 2025 wallet- and account-level inventory produced by the transition and reconcile subsequent transfers, acquisitions, income events, and dispositions so the remaining lots can be traced forward into 2026 and later years.
For broker-held transactions occurring during the Notice 2026-20 relief period, retain contemporaneous evidence of any specific identification made in the taxpayer’s books and records.
Reconcile Forms 1099-DA to the taxpayer’s own lot inventory rather than treating the broker form as a substitute for it.
FAQs
Can I still use HIFO?
HIFO can be implemented only through a valid specific identification. During the Notice 2026-20 relief period ending December 31, 2026, an eligible taxpayer can make the required identification for broker-held units in the taxpayer’s own books and records without communicating it to the broker.
Under current guidance, transactions after the relief period are governed by the permanent adequate-identification rules unless additional relief is issued.
Do I need to amend prior years?
Not automatically. Revenue Procedure 2024-28 is a transition safe harbor, not a rule requiring every taxpayer to amend prior returns.
Whether a prior return requires correction depends on the taxpayer’s actual reporting, the records available to support it, and the applicable statutes of limitation.
What about transfers between my wallets?
Maintain clear, detailed records of transfers of digital asset proceeds , including dates, amounts, and basis, to support your allocations.
What if my software only supports universal basis?
Use it for reconciliation, then export data and perform allocation using tools that support wallet/account-level tracking.
About Camuso CPA
At Camuso CPA, we serve digital asset investors and Web3 businesses with precise tax and accounting services. Our mission is to minimize your tax burden, maintain compliance, and provide peace of mind. We were among the first CPA firms to accept cryptocurrency for professional services.
Contact us today to review the January 1, 2025 allocation and the identification records that apply during the Notice 2026-20 relief period.
Watch the full video: https://youtu.be/UJC0UxcPe9k
Related service: Crypto CPA.
This article is provided by Camuso CPA for general informational purposes and does not constitute legal, tax, accounting, or investment advice. Tax laws and regulations are evolving rapidly and the information presented may not reflect current guidance. Reading this article does not create a CPA-client relationship. For advice on your specific situation, schedule a consultation with Camuso CPA.
Camuso CPA, PLLC